Introducing Rain wallets: embedded stablecoin wallets for the full flow of money
A wallet used to be where stablecoins sat.
Doing anything useful with them often meant stitching together separate providers to get money in, spend it, send it, and move it back into the banking system.
Today, we’re launching Rain wallets: embedded stablecoin wallets built to work seamlessly with the full Rain stack.
Partners can give users one wallet where money can land as stablecoins, be spent with a card, sent onchain, or paid out to bank accounts in local currency.
Cards, virtual accounts, onramps, offramps, rewards, and payouts can all work with the same wallet through one integration.
Non-custodial Rain wallets are available today across multiple blockchains. Custodial wallets and additional capabilities for earning on balances are coming by the end of the year.
One wallet for the full flow of money
A wallet is only useful if users can actually do something with the money inside it.
Rain wallets connect a stablecoin balance to the rest of the Rain stack:
- Receive: Users can receive stablecoins directly, or receive fiat payments through Rain virtual accounts that land as stablecoins.
- Spend: The wallet can back a Rain-issued card, making the balance spendable at 175 million merchant locations.
- Send: Users can send stablecoins onchain or send payouts to bank accounts in local currency across 50+ currencies.
- Earn: Rain rewards can plug into the wallet experience, with additional capabilities for earning on balances planned by the end of the year.
Every balance is ready to use the moment it arrives.
What this looks like for a user
Consider a freelancer in Mexico getting paid by a client in the United States.
Her client sends dollars to a Rain-powered virtual account, and the payment lands in her wallet as stablecoins.
She can spend from that balance with her Rain-issued card. She can send stablecoins onchain. And when she needs to pay someone, she can fund the payment in stablecoins while the recipient gets local currency in their bank account.
All managed from one wallet, inside the financial app she already uses.
She does not need to understand blockchains, gas tokens, seed phrases, or the infrastructure moving money underneath.
Embedded directly into your app
Rain wallets are designed to feel like a familiar financial account rather than a standalone crypto product.
Each user gets their own non-custodial wallet embedded directly into the partner’s app through Rain’s SDKs.
Users can sign in with a passkey or a one-time code sent to their email or phone. There is no seed phrase to write down, and users do not need to acquire gas tokens before making a transaction.
Gas sponsorship, transaction construction, and broadcasting happen under the hood.
Partners design the experience. Rain runs the infrastructure underneath it.
Built to work with the full Rain stack
Rain wallets are built to work seamlessly with Rain’s existing payments infrastructure.
A balance can arrive through a virtual account or onramp, back a Rain-issued card, move onchain, or leave through an offramp or payout to a bank account.
For partners, that means one wallet and one integration covering cards, rewards, virtual accounts, onramps, offramps, and payouts.
Adding a wallet does not have to mean adding another vendor, negotiating another agreement, or reconciling another set of infrastructure against the rest of your program.
Non-custodial by design
Rain’s non-custodial wallets are designed so only the end user can move their funds.
Keys are created and used inside a secure enclave. Neither Rain nor the partner can view or extract them.
The code protecting those keys is open source and independently verifiable, so security teams can inspect the protections themselves.
Recovery is configurable by program. Users can also export their keys and take their wallet elsewhere.
Available across 12 blockchains
Rain non-custodial wallets support 12 blockchains today:
- Ethereum
- Polygon
- Base
- Celo
- Optimism
- BNB Smart Chain
- Avalanche
- Arbitrum
- ZKsync
- Monad
- Solana
- Plasma
Rain wallets support USDC, USDT, and other supported stablecoins, with availability varying by network.
Partners are not tied to one chain or one stablecoin.
Open and modular
Rain wallets are built to work seamlessly with the full Rain stack, but partners are not required to use them.
Partners that already use another wallet provider can keep it and plug into Rain cards, rewards, virtual accounts, onramps, offramps, and payouts.
That flexibility is intentional. Rain is building a full-stack stablecoin platform without turning it into a closed system.
The wallet at the center of the account
Rain started by making stablecoins compatible with daily spending through cards.
Virtual accounts, onramps, offramps, and payouts connected stablecoins to the banking system.
Rain wallets bring those pieces together around one balance.
The wallet can become the centerpiece of a primary financial account: one where a user can get paid, earn rewards, spend with a card, send money onchain, and pay out to a bank account in local currency.
That’s the idea behind Rain wallets:
One stablecoin balance that works across the financial system.
Non-custodial Rain wallets are available to Rain partners today. Custodial wallets and additional capabilities for earning on balances are planned by the end of 2026.
State of payments in the Asia-Pacific region
Key takeaways
- APAC has built some of the world’s most advanced domestic payment systems. Fast payment and QR networks make local payments nearly instant and inexpensive. Stablecoins are in the early stages of plugging into those existing rails.
- Cross-border payments remain the bigger challenge. APAC lacks a common currency or unified payment rail across the region. Efforts to connect national systems are still largely limited to retail transfers and businesses remain heavily reliant on correspondent banking.
- Asia is the largest source of stablecoin payment volume on an annualized basis. Payments sent from the region account for about $245 billion, or 60% of the global total, with activity concentrated in Singapore, Hong Kong, and Japan.
- Regulation is advancing faster than local-currency stablecoin adoption. APAC markets are creating frameworks for regulated stablecoins, but more than 99% of the global market remains dollar-denominated. The next year will test whether new local-currency tokens and cross-border connections gain meaningful usage.
Executive summary
The Asia-Pacific region is one of the world’s largest and most dynamic payments markets. Home to 60% of the world’s population, the region is projected to generate $1.3 trillion in payments revenue by 2030, with more than half coming from corporate payments.
Within the region’s individual markets, payment infrastructure is developed and effective. Real-time account-to-account systems, mobile wallets, and national QR standards have made domestic payments fast, inexpensive, and widely accessible. But those systems were largely built within national borders. Moving money between APAC markets and outside of the region remains slower and more complicated, particularly for businesses.
Stablecoins are beginning to address some of these gaps. Asia is a major source of stablecoin activity, primarily for trading and payments. Stablecoin business payments in Asia are concentrated in financial hubs including Singapore, Hong Kong, and Japan. Across APAC, stablecoins are in the early stages of connecting with existing infrastructure rather than competing with it.
Simultaneously, regulation is reshaping the market. Japan and Hong Kong have established stablecoin regimes, Singapore has published draft legislation to implement its framework, and several other APAC markets are developing their own approaches. Many of these efforts are creating paths for local-currency stablecoins, even as the global stablecoin market remains overwhelmingly denominated in US dollars.
This report examines why domestic payments in APAC work so well, where infrastructure still falls short, how stablecoins are being used today, and where regulations stand across the region.
Domestic payments are fast, cheap, and reliable
APAC markets have developed some of the most effective domestic payment infrastructure in the world. The region took a different path than the United States and built its cashless layer on account-to-account rails as opposed to card networks. These systems are now fast, low-cost, and deeply embedded in everyday commerce, raising the bar for any new payment method to compete at the domestic checkout.
Most APAC markets have a domestic fast payment system that allows users to pay individuals and businesses instantly at any time. Banks and digital wallets connect to these common rails, and standardized QR codes allow merchants to accept payments across participating apps. Among the emerging and developing economies that report payment data to the Bank for International Settlements (BIS), fast payments made up 49% of cashless payments in 2024, against about 10% in advanced economies. Across Southeast Asia, penetration of mobile wallets and QR payments surpassed 80% of the population in 2023.
In Malaysia, national payment network PayNet processed 8.44 billion digital payment transactions in 2025. Transactions on DuitNow QR, Malaysia’s standardized national QR code payment system, more than doubled in 2025 to 3 billion. In the Philippines, standardized QR code transactions overtook card transactions for the first time in 2025.
Two of APAC’s largest economies, China and India, have similarly high levels of digital payment adoption, but they got there in very different ways. China’s path was private-led. Alipay and WeChat Pay built proprietary payment ecosystems that came to dominate everyday commerce, initially maintaining direct connections with banks. The People’s Bank of China in 2017 said non-bank payments would be required to clear through NetsUnion, a centralized clearing platform that sits between payment companies and banks. India ran the sequence in reverse. UPI launched in 2016 as interoperable national payment infrastructure, operated by the National Payments Corporation of India. The shared system provided the rails, while private apps competed for users on top of them.
The national fast systems are intentionally inexpensive, particularly for smaller transactions. Account-to-account payments typically carry no credit risk and low interchange, keeping operating costs lower than card networks. Many markets also place caps on fees. India eliminated merchant fees on UPI in 2020 and updated the policy in September 2026. From October 15, 2026, a 0.4% fee will apply to certain UPI merchant payments above ₹2,000, while person-to-person transfers remain free.
Alongside the national fast systems, cards remain important, particularly in the region’s developed markets. APAC card payment value reached an estimated $23.7 trillion in 2024, and in Japan credit cards accounted for 82.7% of cashless spending by value in 2025. More than 29 million credit cards were in circulation in Hong Kong at the end of the first quarter of 2026, a 33.4% increase year-over-year.
Given that much of the region has instant, inexpensive, and widely accepted domestic payment rails, stablecoins—on the surface, at least—don’t have an immediate path to adoption. Consumers and merchants are unlikely to adopt a new technology that would offer little additional benefit, but stablecoins do have an entry point through existing rails.
Cards are the clearest example. Stablecoin card programs connect stablecoin balances to existing card networks, allowing consumers to spend them wherever those networks are accepted without requiring merchants to adopt new infrastructure. Stablecoin-linked card spending reached $4.5 billion globally in 2025, up 673% from 2024, according to McKinsey. In the 12 months to August 2026, Rain cardholders spent around $500 million on stablecoin cards at APAC merchants.
There have also been early efforts to expand existing domestic rails to support stablecoins. HSBC plans to make its upcoming Hong Kong dollar stablecoin available for payments through its mobile wallet, PayMe. Thailand’s finance ministry also announced an 18-month sandbox in 2025 that allows visitors to convert crypto to baht and pay merchants through the country’s existing QR payment system. Both suggest stablecoins could reach domestic commerce through payment methods consumers and merchants already use rather than entering as a competing rail.
Cross-border payments show the friction
While many APAC markets have effectively solved domestic payments with national fast payment systems, these rails today are largely ineffective when it comes to cross-border payments. Each system was built for one country and its local currency. International payments still mostly require going through the correspondent banking system, converting currencies, and, in several markets, adhering to capital controls.
This structural disadvantage sets APAC apart from the other large payments markets. The eurozone removed most intra-regional currency exchange friction with the euro, and the US has the benefit of issuing the currency used in 89% of foreign exchange transactions. APAC has a robust remittance market, but neither advantage.
Four of the world’s five largest remittance recipient countries are in Asia, according to the World Bank’s December 2024 estimates: India, China, the Philippines, and Pakistan. The Philippines received a record $39.62 billion in personal remittances in 2025, and Pakistan received $41.6 billion in the fiscal year to June 2026.
Moving that money remains expensive and slow, though the burden varies significantly by channel. In the third quarter of 2025, sending $200 to East Asia and the Pacific cost an average of 5.83%. But that regional average masks a wide gap in how people send money. Globally, digital remittances cost an average of 4.59%, compared with 7.30% for cash and other non-digital channels and 14.99% for bank transfers. Someone sending money through a digital app may therefore pay considerably less than the headline figure suggests, while someone relying on a bank can pay more than twice the regional average. In October 2025, the Financial Stability Board found that just 0.5% of business-to-business payments sent from East Asia and the Pacific were credited within an hour, compared with 28% of person-to-person payments.
To reduce some of that friction, central banks across Asia have begun connecting their domestic payment systems. Singapore's PayNow links to India's UPI, Thailand's PromptPay, and Malaysia's DuitNow. Indonesia's QRIS works in Malaysia, Thailand, Singapore, and Japan. Project Nexus, incubated at the BIS and targeted to launch in 2027, plans to go further and connect national systems from its five founding markets: India, Malaysia, the Philippines, Singapore, and Thailand. Indonesia also joined Project Nexus in 2026.
Where these linked networks fall short is that they’re currently regional. The US, the top remittance sender in the world, has no comparable universal real-time retail system. The European Central Bank in 2025 said it would “start the realization phase” of connecting TIPS, its instant payment system, to India’s UPI. The pilot is scheduled to go live in the first half of 2027.
APAC’s connected systems are also limited in the type and size of transaction they can support. Every PayNow link—to India, Thailand, and Malaysia—caps transfers at SGD 1,000 per user per day and allows only person-to-person payments. The QR links work the other way, for merchant payments only, with no way to send money to individuals. Across all 29 QR and person-to-person linkages ASEAN counted at the end of 2025, the payment volume for the year was about $1 billion, a small fraction of the total value transferred outside of these systems.
Project Nexus is also being built for retail payments, and the BIS says the transaction caps mean the program “could not practically be used to send high-value ‘wholesale’ payments between financial institutions.”
Central banks in APAC have also experimented with settling cross-border transactions with wholesale central bank digital currencies (CBDCs), mostly for trade. mBridge is one of the most advanced multi-CBDC platforms in use today. Developed jointly by the BIS Innovation Hub and the central banks of Hong Kong, Thailand, China, and the United Arab Emirates, mBridge facilitated over $22 million in payment and foreign exchange transactions during a six-week pilot in 2022. The BIS left mBridge in 2024, saying that while the project no longer needed the BIS’s support, it was “not mature enough to start operating.” mBridge is still running, although with different participants. Saudi Arabia later withdrew and Macao and Mongolia joined in 2026.
Globally, stablecoins are emerging as an alternative to traditional remittance rails, offering a faster and cheaper way to send money internationally. Cross-border stablecoin transfers rose 77.5% in the year to June 2026, reaching $220.3 billion. Chainalysis found cross-border stablecoin activity exceeded domestic activity in every Central and Southeast Asian and Oceanian market it analyzed, 3.2 to 1 across the region. The average cross-border payment was about $3,000, a size Chainalysis calls "far too small to be institutional," suggesting the activity is driven by retail users and small businesses as opposed to institutions. PDAX CEO Nichel Gaba estimates that 5% to 10% of remittances sent to the Philippines are being settled in stablecoins.
Solana is seeing a similar pattern on its network. Remittances in emerging markets, including the Philippines and across South and Southeast Asia, are “the one consumer use case that has genuinely crossed beyond crypto-native users,” said Anna Zhang, Head of Payment Growth, APAC at the Solana Foundation. Remittances and B2B settlement are also the network’s fastest-growing payment segments, particularly for corridors ending in India and the Philippines, Zhang said.
Where stablecoin volume is today
Stablecoin activity in APAC falls into two main categories: trading and payments. Globally, crypto trading is the biggest driver of stablecoin transaction volume, accounting for about 88% according to a May 2025 Boston Consulting Group report.
In APAC, trading is most prevalent in South Korea. Korean exchanges Bithumb and Coinone began listing Tether's USDT against the won in December 2023, and by mid-2025 the won was the second most traded currency against USDT after the US dollar, at about $124 million a day on centralized exchanges, roughly level with the euro. Korea's crypto economy grew 12.3% to $449 billion in the year to June 2026, driven by retail trading, according to Chainalysis. Thailand ranks second in the region for stablecoin purchases with local currency. Baht purchases of stablecoins reached about $9.4 billion in the year to June 2025.
Payments are a smaller share of stablecoin activity, but APAC leads the world in them. McKinsey estimates global stablecoin payments more than doubled in 2025, accounting for $390 billion in annualized volume. About $245 billion of that, or 60%, was sent from Asia, against $95 billion from North America, $50 billion from Europe, and less than $1 billion each from Latin America and Africa.
Despite a ban on crypto trading and related services in place since 2021, China has a crypto economy Chainalysis sizes at $176.3 billion. The number of unique wallets sending stablecoin peer-to-peer transactions grew 43 times between early 2024 and mid-2026, and monthly domestic stablecoin payments grew from about $240 million in March 2025 to nearly $5 billion a year later.
Within stablecoin payments globally, B2B transfers are the largest, estimated to be about $226 billion annualized from December 2025 activity. A May 2025 study from Artemis, Castle Island Ventures, and Dragonfly found the Singapore to China corridor to be the most active among the payment firms it surveyed, with Singapore, Hong Kong, and Japan in the top five sending countries globally. Singapore's institutional-platform activity rose 94% to $60 billion in the year to June 2026.
Stablecoins are gaining regulatory clarity
Stablecoin regulation is taking shape across APAC, following a familiar model. Like the US under the GENIUS Act and the EU under MiCA, stablecoins are coming inside the regulatory perimeter through licensing, reserve requirements, and redemption rules. In Hong Kong and Japan, similar to the EU, some of the first licensed issuers have leaned toward local-currency tokens, even as stablecoin demand remains overwhelmingly dollar-denominated.
Japan, Hong Kong, and Singapore have some of the most robust stablecoin policy frameworks in the region. Japan permits banks, funds transfer service providers, and certain trust institutions to issue stablecoins under its Payment Services Act, while Hong Kong’s Stablecoins Ordinance took effect in August 2025 and produced its first two licensed issuers in April 2026. Singapore finalized its framework in 2023 and is now implementing it through legislation.
Despite more than 99% of stablecoins in circulation globally being US dollar-backed, local-currency stablecoins are emerging across APAC. Japan's first registered yen stablecoin, JPYC, launched in October 2025. KRW1, issued by BDACS and backed by Korean won reserves held at Woori Bank, is the first Korean won stablecoin. In September 2026, Rain added support for KRW1, making it spendable at more than 175 million Visa merchant locations around the world. Thailand's central bank says its design study for a baht stablecoin is in its final stage, with regulations expected within 2026 or early 2027. Hong Kong's first two licensed issuers are both focused on Hong Kong dollar tokens. Anchorpoint began a phased rollout of HKDAP in August 2026, while HSBC plans to launch its Hong Kong dollar stablecoin later this year.
APAC’s local-currency stablecoins in circulation have seen limited adoption. As of September 2026, stablecoins backed by the Australian dollar, Singapore dollar, and rupiah collectively had about $30 million in circulation, and JPYC had issued a cumulative ¥10 billion, or about $67 million.
Euro-backed stablecoins also make up a small portion of the total market, although they’ve had a head start—the first of these tokens were issued years before the first local-currency APAC stablecoins hit the market. Euro-backed stablecoins have a total circulating supply of around $800 million, compared with more than $290 billion for US dollar-pegged stablecoins.
What to watch
Whether or not stablecoin adoption accelerates will largely depend on whether stablecoins can connect to the existing payment infrastructure in APAC. This is particularly true when it comes to domestic payments, given how effective the rails are today. There are some early examples of stablecoins entering through established systems, one of which is stablecoin cards.
When it comes to cross-border payments, stablecoins have a clearer use case. Efforts to link domestic payment systems across APAC have so far been focused on retail payments, while institutions are still reliant on traditional correspondent banking rails.
Regulation could expand the ways stablecoins enter both domestic and cross-border payment flows. Japan and Hong Kong have established stablecoin regimes, Singapore is implementing its framework, and new local-currency tokens are reaching the market. But regulatory clarity has yet to translate into meaningful adoption of those tokens, leaving an open question around what demand develops as more regulated products become available.
Rain files application with the OCC to establish Rain National Trust Bank
Proposed national trust bank will bring custody, stablecoin reserve management, and stablecoin issuance and redemption for the payments ecosystem under federal supervision
Former Square Financial Services CFO Brandon Soto named proposed President and CEO
Key facts
- Rain has filed an application with the Office of the Comptroller of the Currency (OCC) to establish Rain National Trust Bank (RNTB), a proposed national trust bank headquartered in New York.
- If approved, Rain National Trust Bank will provide fiduciary custody of digital assets and US dollars, reserve management for permitted stablecoin issuers, and issuance and redemption of US dollar-backed stablecoins for institutional clients.
- Rain National Trust Bank will not accept deposits, offer consumer accounts, or make commercial loans.
- Brandon Soto, former Chief Financial Officer of Square Financial Services and most recently Chief Financial Officer of Coastal Financial Corporation, will serve as the proposed President and CEO of Rain National Trust Bank.
Rain, the enterprise-grade infrastructure for stablecoin payments, announced today that it has filed an application with the Office of the Comptroller of the Currency (OCC) to establish Rain National Trust Bank (RNTB), a proposed national trust bank headquartered in New York. If approved, RNTB will bring the custody, reserve management, and stablecoin issuance and redemption functions behind Rain partners' programs under a single federal supervisory framework. Rain also announced that Brandon Soto will serve as RNTB's proposed President and Chief Executive Officer.
Rain's partners run stablecoin card, wallet, and money movement programs for millions of end users. Today the assets behind those programs sit across state licenses, third-party custodians, and third-party stablecoin issuers. A national trust bank will allow Rain to expand its offerings to include fiduciary custody of assets under OCC supervision and examination, and to issue and redeem stablecoins.
"The institutions building on Rain want the assets behind their programs held by a fiduciary that answers to a federal regulator," said Farooq Malik, CEO and co-founder of Rain. "Rain National Trust Bank is how we plan to meet that expectation. Rain remains a payments platform. The proposed trust bank will be a separate subsidiary that holds client assets in custody, as a fiduciary and subject to OCC examination."
What Rain National Trust Bank will do
If approved, RNTB will serve institutional clients in the digital asset payment ecosystem through three lines of business:
- Custody: Safeguard approved digital and fiat assets as a fiduciary, with client assets segregated from the proposed bank's own assets.
- Reserve management: Hold and administer reserves for permitted stablecoin issuers under the GENIUS Act.
- Issuance and redemption: Issue US dollar-backed stablecoins as issuer of record in accordance with the GENIUS Act.
What Rain National Trust Bank will not do
If approved, as an uninsured national trust bank, RNTB will not accept deposits and will not make commercial loans. Assets held by RNTB for clients will be custody assets held for identified owners, not liabilities of the bank, and the reserves backing any stablecoin RNTB issues will not be pledged, lent, or reused. RNTB will not offer consumer accounts. Rain is not a bank and will remain a stablecoin payments platform and a Visa and Mastercard Principal Member through its other subsidiaries; RNTB will be a separately capitalized subsidiary supervised and examined by the OCC.
Leadership
Brandon Soto will serve as proposed President and Chief Executive Officer of RNTB, subject to OCC review. Soto was most recently Executive Vice President and Chief Financial Officer of Coastal Financial Corporation. Before that he was Chief Financial Officer of Square Financial Services, Inc., Block's Utah-chartered industrial bank, where he helped prepare the charter application approved by the FDIC and the Utah Department of Financial Institutions and led finance, treasury, and capital management. Earlier he served as Chief Financial Officer and Chief Administrative Officer of Green Dot Bank.
"A trust bank’s first job is simple. Know what you hold, know who you hold it for, and keep it safe," said Soto. "I have sat across from bank examiners for twenty years, and the best answer you can give is, ‘Here’s the reconciliation.’ That is the discipline we are building into the proposed national trust bank from day one. Clear ownership, daily reconciliation, strong controls, and the right level of capital."
What happens next
The application is subject to OCC review and approval, including a public comment period. The public portion of the application will be available on the OCC's website at occ.gov. Rain leadership and RNTB's organizers recognize the responsibility that comes with seeking a national trust bank charter and will work diligently with the OCC throughout the process.
Rain worked with Paul Hastings in preparing the application.
Frequently Asked Questions
Question: What is Rain National Trust Bank?
Answer: Rain National Trust Bank (RNTB) is a proposed national trust bank. Rain has filed an application with the Office of the Comptroller of the Currency (OCC) to establish it. If approved, RNTB will be a separately capitalized subsidiary of Rain, headquartered in New York, supervised and examined by the OCC, and limited to the operations of an uninsured trust bank, including: fiduciary custody of digital assets and US dollars, reserve management for permitted stablecoin issuers, and issuance and redemption of US dollar-backed stablecoins for institutional clients. RNTB has not yet been approved and will only begin operations after receiving all required OCC approvals.
Question: Is Rain becoming a bank?
Answer: Rain is applying to establish a separate, limited-purpose trust bank subsidiary. Rain itself remains a stablecoin payments platform and a Visa and Mastercard Principal Member, and that does not change. Rain National Trust Bank will be a separately capitalized subsidiary of Rain with a limited purpose: holding client assets as a fiduciary, managing stablecoin reserves, and issuing and redeeming stablecoins, all under OCC supervision. Rain National Trust Bank will be an uninsured trust bank and will not accept deposits and will not make commercial loans.
Question: Will Rain National Trust Bank be FDIC insured?
Answer: No. Rain National Trust Bank will not accept deposits and will not be FDIC insured. Assets held by Rain National Trust Bank for clients will be custody assets held for identified owners, segregated from RNTB's own assets, not liabilities of RNTB.
Question: What will Rain National Trust Bank do?
Answer: If approved, Rain National Trust Bank will operate three lines of business for institutional clients. Custody: safekeeping of approved digital and fiat assets as a fiduciary. Reserve management: custody and administration of reserves for permitted stablecoin issuers under the GENIUS Act. Issuance and redemption: issuing US dollar-backed stablecoins as issuer of record.
Question: Who is the proposed President and CEO of Rain National Trust Bank?
Answer: Brandon Soto is the proposed President and Chief Executive Officer of Rain National Trust Bank. He was most recently Executive Vice President and Chief Financial Officer of Coastal Financial Corporation, and previously Chief Financial Officer of Square Financial Services, Inc., Block's Utah-chartered industrial bank, where he helped prepare the bank's charter application and led finance, treasury, and capital management. He earlier served as Chief Financial Officer and Chief Administrative Officer of Green Dot Bank. He is a CPA.
Question: Does this change Rain's card programs or partnerships?
Answer: No. Rain's card, wallet, and money movement programs continue as they operate today, and Rain continues to work with its existing partners. Rain National Trust Bank is a multi-year initiative that, if approved, will add a federally supervised option for custody, reserve management, and stablecoin issuance and redemption alongside the infrastructure Rain and its partners use today.
Question: When will the OCC decide on Rain National Trust Bank?
Answer: The OCC's review follows its own process and timeline, which includes a public comment period. The public portion of the application will be available on the OCC's website over the coming days, and Rain National Trust Bank can begin operations only after receiving all required approvals.
Read original press release here: https://www.prnewswire.com/news-releases/rain-files-application-with-the-occ-to-establish-rain-national-trust-bank-302898950.html?tc=eml_cleartime
How to launch dollar accounts in Latin America using stablecoins
It’s no secret that Latin Americans like having dollar access. Whether it's shops in Bolivia pricing goods in USDT or ARQ / DolarApp giving Mexicans dollar accounts to pay for Netflix, the use cases are more than just uno o dos.
Launching a dollar account in Latin America used to be a multi-year project costing millions of dollars and fully reliant upon traditional bank partners. Today it can be a weeks-long integration thanks to modern stablecoin infrastructure. And the best part is that your customers do not have to know which rails you're using. Ni se enteran.
With a stablecoin-powered solution, your users can open your app, see a balance in dollars, send some of it to a family member, and tap their card at a store in Mexico City or Miami. Nothing about that experience asks them to understand stablecoins, non-custodial wallets, or blockchains. All of that complexity stays entirely underneath a familiar and user-friendly front end.
We spend most of our week in conversation with fintechs, neobanks, remittance companies, and marketplace platforms across Mexico, Argentina, Colombia, Bolivia, and beyond. As recently as two months ago, dollar accounts were talked about as a someday project. But now that the largest players in the region are actively rolling them out, these future ambitions have become immediate priorities.
The good news is that launching a global account no longer requires rebuilding your entire stack. Rain’s expertise can help teams launch a full dollar account experience in weeks, or add only the pieces you need to what you've already built.
Why your users actually want dollars
The reasons why Argentines or Colombians, for example, want dollars is not uniform. And we don’t mean that one is for yerba mate and the other is for arepas… In fact, we have seen multiple reasons for this growing demand for dollar accounts. They include:
- Holding dollars: Some users simply prefer to keep part of their balance in dollars, particularly when they expect to spend, send, or receive money in dollars.
- Receiving money from abroad: Remittances, and increasingly freelance and contract income paid by clients in the US or Europe.
- Paying for things priced in dollars: Cloud services, software and AI subscriptions, suppliers, and contractors.
- Travel: Spending abroad with a local-currency card can mean high FX costs and unexpected declines.
- Business operations: Small and mid-size businesses across the region increasingly invoice and pay in dollars.
Many times, users solve these problems through an informal exchange, with an account at a foreign fintech, or by holding stablecoins in a wallet that has nothing to do with your app. Every one of those workarounds, however, is money that has left your product.
Dollar accounts used to be a two-year project
Integrating US dollar accounts into your platform historically meant finding a US sponsor bank willing to take on customers in your market. Then came the correspondent relationships, the account structure that holds customer funds, the minimum balances, and a compliance review that took several quarters to complete.
If you then wanted to make that dollar balance spendable, the process began again. Card issuing was arranged market by market, with a separate partner, a separate contract, and a separate integration in each country. You were required to prefund settlement accounts in multiple markets with capital that sat idle for days and did nothing for your bottom line.
As a result, dollar accounts were only within reach for institutions large enough to absorb that cost, and the products they shipped were often narrow in who could open one and what they could do with it.
The architecture of a stablecoin-powered dollar account
USD-backed stablecoins, like USDC or USDT, and accompanying infrastructure unlock dollar balances that can be securely stored and easily spent, without needing to build a banking relationship in another country or introduce friction into the user experience.
The stablecoin plumbing that makes this all possible includes:
- Onramps & virtual accounts: Turn local currency into USD-backed stablecoins.
- Wallets: Store stablecoins securely within your app.
- Cards: A branded card backed by the stablecoin balance and accepted everywhere Visa or Mastercard are accepted.
- Offramps: Turn stablecoins back into local currency.
For builders and fintech nerds looking for a deeper dive, check out our Anatomy of a Stablecoin Card Swipe.
How to launch: start with the pieces you need
If you are starting from scratch, Rain provides the full suite of tooling needed to launch full-fledged dollar accounts in weeks.
However, almost nobody we talk to across Latin America is starting from zero, and we understand the reluctance to rebuild what may already exist. That’s why Rain has built its stablecoin payments infrastructure to be modular and interoperable with other technologies. Almost any team can add the pieces they need to give users dollar access, without replacing what already works.
If you already offer a USD balance, Rain can issue a card to make those funds spendable, which is usually the difference between dollar accounts that people just try and accounts they want to fund every single month.
If you already have a card, Rain’s technology allows you to add the wallet, onramps, and offramps around it. Your product stops being a local-currency card and becomes a spending layer around a dollar balance, which changes what the product is worth to your user without changing the thing they already carry.
There is also a strong case to be made for upgrading an existing card program to a stablecoin card, for two reasons. The first is settlement. Traditional card programs settle over multiple days, which means you have to park capital in prefunded accounts. Rain settles card transactions with the networks daily using stablecoins, which reduces the amount of capital required to be parked for settlement. The second is reach. Traditional issuing is arranged country by country, so expansion means a new partner, a new integration, and a new operating model each time. Rain supports multi-region issuance through a single integration.
Where this is heading
Dollar access in Latin America is moving from a premium feature to a baseline expectation. The companies that embrace stablecoin solutions will ship these offerings by next quarter, all while keeping the user experience familiar and trusted.
If you are working through what this looks like for your product, we’d love to arrange time to compare notes and outline a potential solution for you. Please reach out to us at sales@rain.xyz.
Introducing real-time funding
Stablecoin cards have traditionally required users to manage two balances: the one in their wallet and the one powering their card’s spending limit.
Before making a purchase, users have had to allocate stablecoins to a separate collateral contract. When that balance runs low, they have to replenish it.
Real-time funding removes that loop.
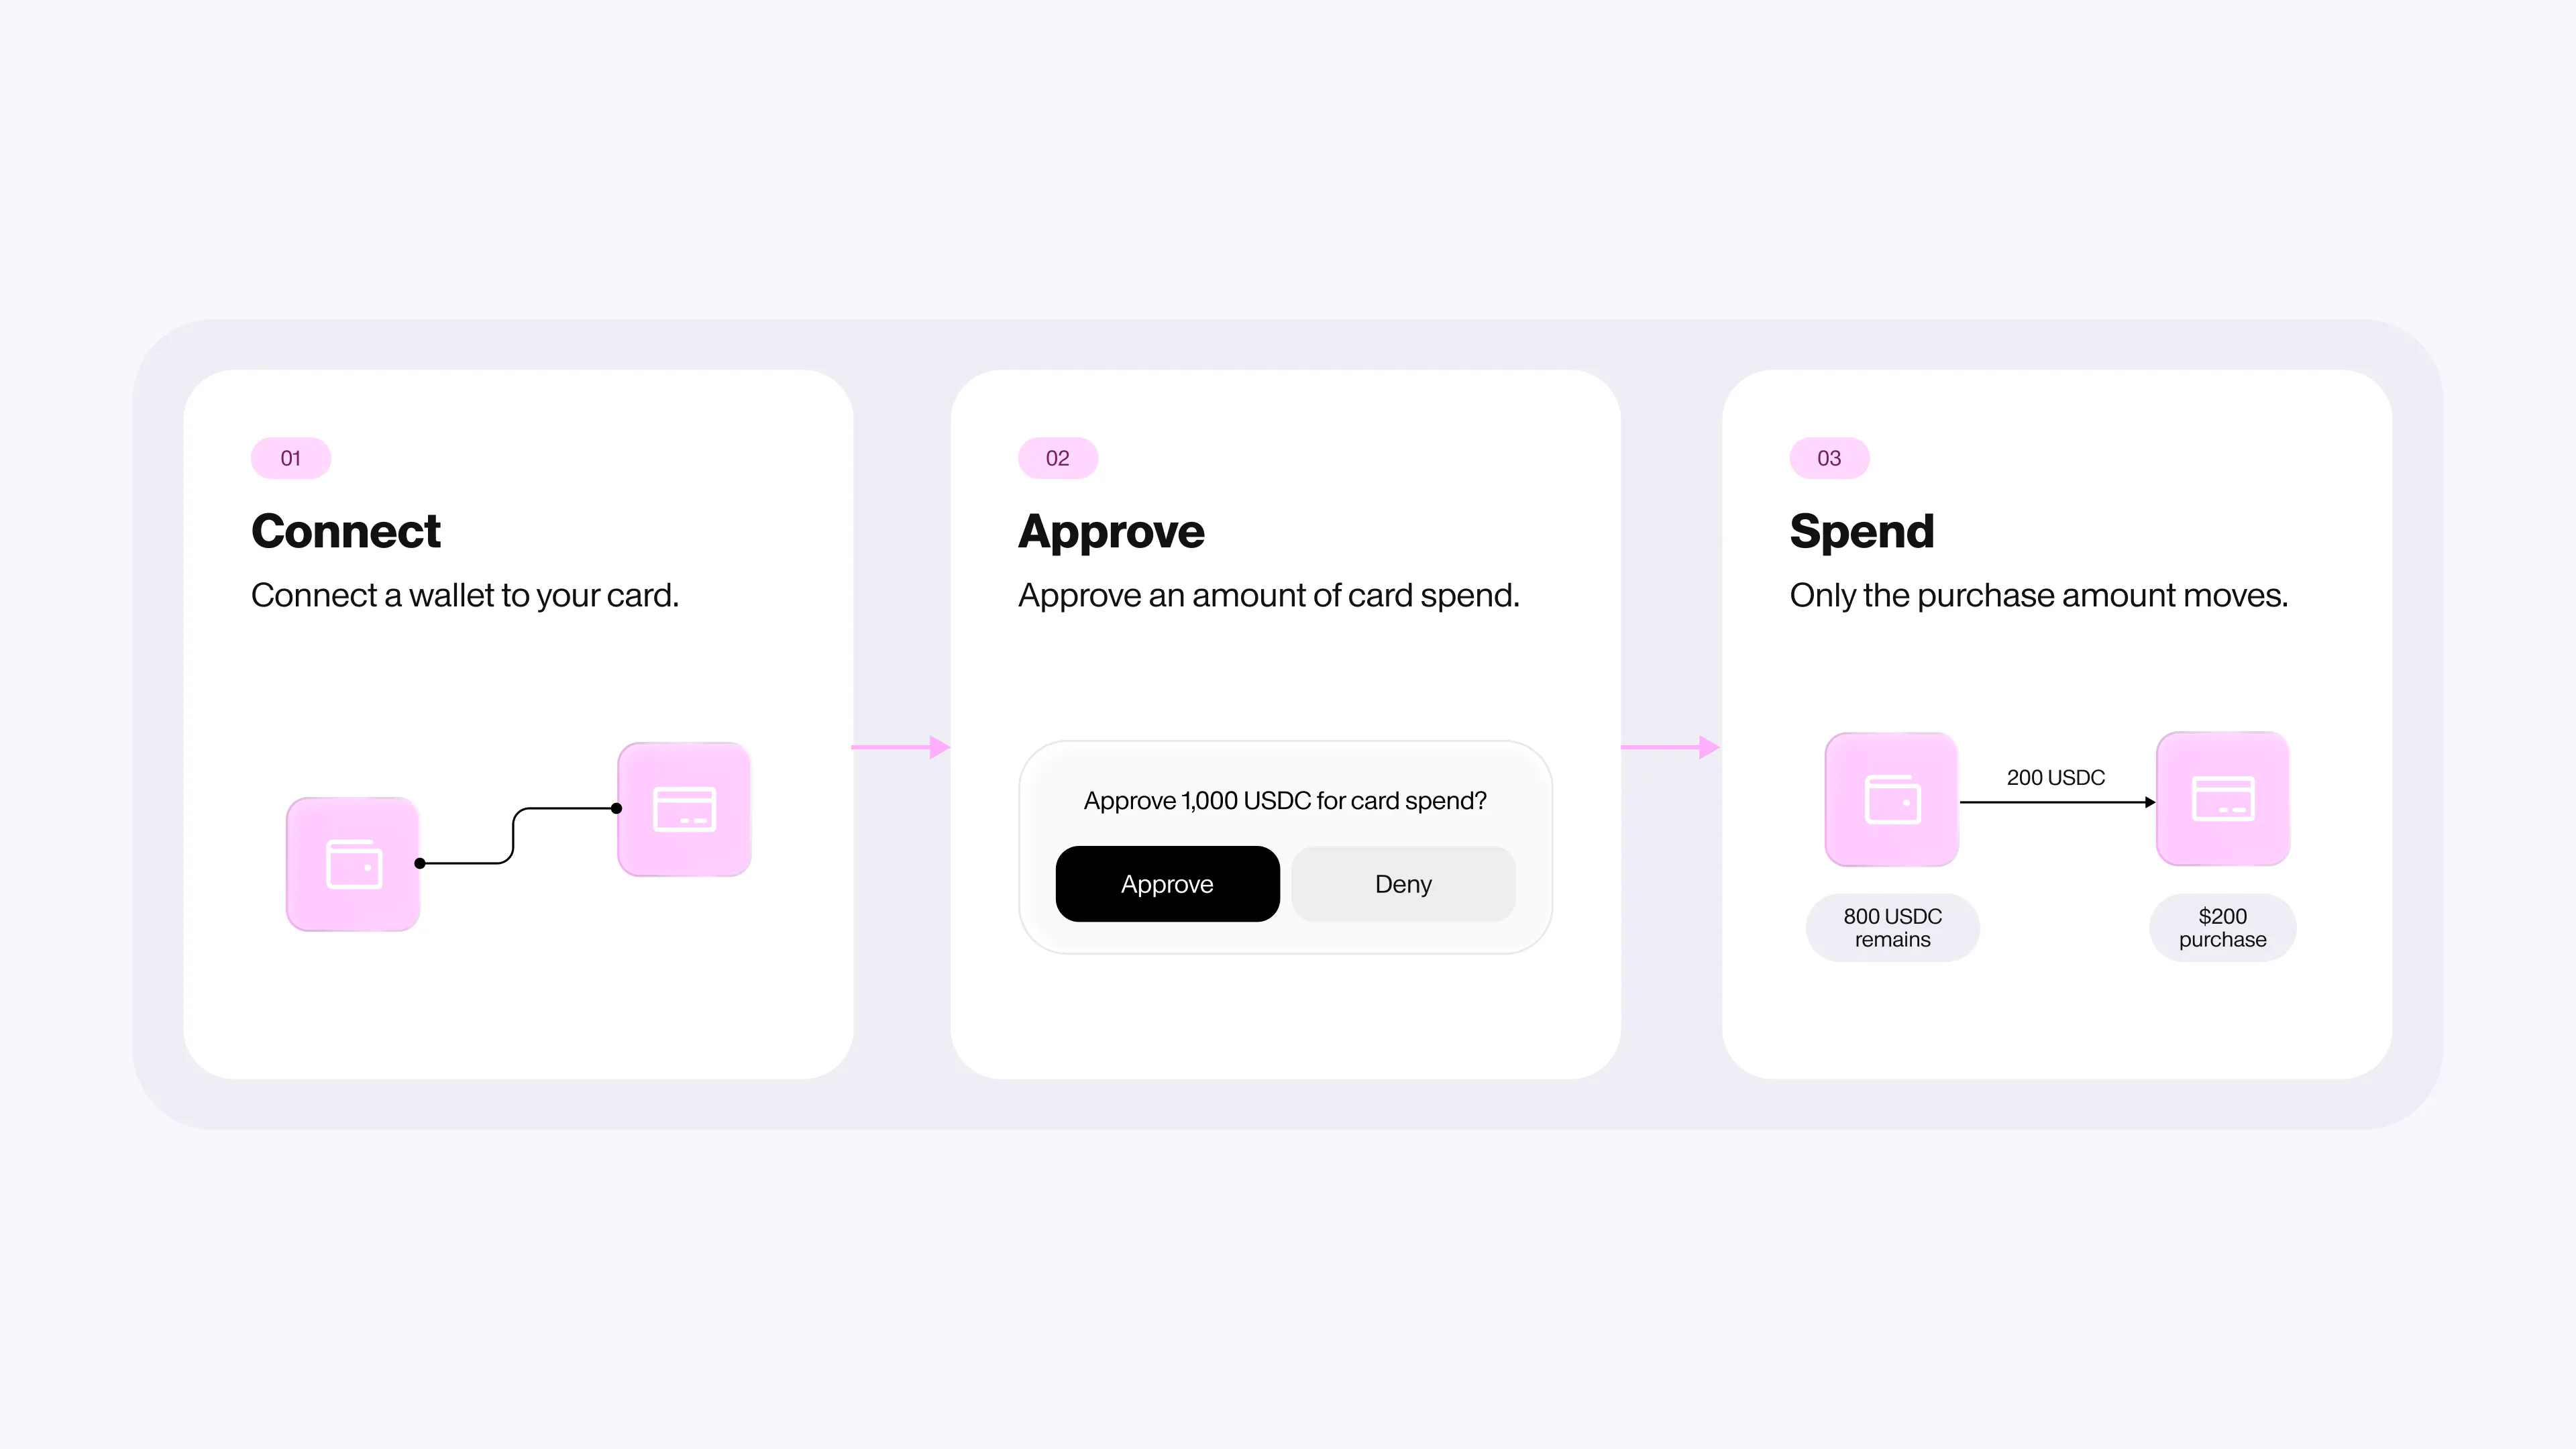
With real-time funding, users connect a wallet and approve how much their card can spend. From there, each purchase is authorized against the wallet balance in real time. Only the amount needed is committed to the collateral contract at authorization, where it stays until settlement. The rest stays in the user's wallet. The approval is revocable at any time.
One balance to manage
Until now, a stablecoin cardholder could have plenty of funds in their wallet and still need to maintain a separate balance behind their card.
Real-time funding changes that.
Instead of allocating stablecoins into a collateral contract before spending, the user keeps their funds in their wallet until they are needed for a transaction. Authorization handles the rest, removing the need for users to monitor and repeatedly replenish a separate balance.
For card programs, that creates a simpler experience at both ends of the user journey.
New cardholders no longer need to complete a separate step before making their first purchase. Existing cardholders no longer need to remember to replenish a separate balance to increase spending power.
Connect a wallet. Approve once. Spend.
How real-time funding works
The user first connects a supported wallet and approves how much their card can spend.
When they make a purchase, only the amount needed for that transaction is committed to the collateral contract during authorization, where it remains until it is liquidated to repay Rain’s extension of credit to the user. The remaining balance stays in the wallet.
For example, imagine a user has 1,000 USDC in their wallet and has approved that full balance for card spend.
They make a $200 purchase.
At authorization, 200 USDC is committed to back the transaction. The remaining 800 USDC stays in the user's wallet.
The underlying collateral model does not change. Each user still has their own collateral contract backing authorized card transactions. Real-time funding changes when that contract is funded, shifting the funding trigger into the authorization flow instead of requiring the user to fund it in advance.
Built for smoother card activation
The initial setup is one of the places new cardholders can stall.
They have to allocate stablecoins to a contract, wait for confirmation, and understand why a separate balance is necessary before they can use their card. Real-time funding removes that step from the path to a first transaction.
After activation, the experience stays simpler because there is no separate balance for the user to keep monitoring and replenishing.
For partners, that means fewer steps to put in front of users and a more intuitive path from wallet to spend.
Available in beta
Real-time funding is currently in beta for card programs where Rain manages authorization infrastructure.
At launch, supported assets and networks include:
- USDC on Base
- USDC on Arbitrum
- USDT0 on Plasma
More chains and assets will follow.
General availability is coming soon.
To learn more about real-time funding or discuss enabling it for your card program, visit the Rain documentation or contact your Rain account team.
University of Michigan Athletics and Uptop launch Wolverine Rewards to ignite unforgettable fan moments
One program turns fan support and daily spend into tickets, gear, and access.
University of Michigan Athletics announced today the launch of Wolverine Rewards, a new fan engagement and loyalty program created in partnership with Uptop, a Rain company. Wolverine Rewards gives Michigan fans another way to be rewarded and recognized for the ways they already support Michigan Athletics. The new program enables fast, reliable earning and redemption for fans by leveraging Uptop’s technology, and infrastructure built on Avalanche. The agreement with Uptop was facilitated by Learfield’s Michigan Sports Properties, the exclusive multimedia rights holder of Michigan Athletics.
Wolverine Rewards will be available to students, alumni and fans at wolverinerewards.com and inside the Michigan Athletics official mobile app starting September 16. Fans create a free account and can link a credit or debit card they already carry, then earn in several ways such as attending events across every major Michigan sport, spending inside Michigan Athletics venues and shopping with participating partners including Meijer, Coca-Cola, CITGO and more. Fans can redeem points for merchandise, memorabilia, tickets and exclusive Michigan Athletics experiences.
Most loyalty programs make the fan do the work. Wolverine Rewards was designed to put Michigan fans first. When a fan links an existing debit/credit card, Uptop recognizes all qualifying purchases at participating merchants automatically, adding points to the fan’s balance nearly instantly, allowing them to redeem as soon as they wish.
“We have fans who plan their Fall around seven Saturdays and students who never miss a basketball game, and until now we had no single way to recognize either of them,” said Jennifer Cadicamo, Vice President and General Manager, Learfield’s Michigan Sports Properties. “Wolverine Rewards gives us one program that reaches every seat in our venues and well beyond those walls 24/7/365. We are making it easier for people to keep showing up and then thanking them properly when they do.”
“Fan loyalty programs usually fail because they contradict their mission. They aren’t putting the fan first. In too many cases, they ask people to remember to do something at checkout,” said Zac Sebo, Head of Partnerships, Uptop. “We are removing that friction for Michigan fans. Just link a card once and the program operates in the background. Fans can then redeem tickets or gear with the points while Michigan can better understand where their fans are engaging and choosing to spend.”
Wolverine Rewards will widen after launch, giving fans additional opportunities to benefit. A loaded value credential is planned to be released in the near future. Fans will be able to fund it through their Wolverine Rewards account and use it anywhere they shop, which extends earning well past Michigan venues and partner locations. Michigan and Uptop also plan to add more partner offers and new redemption tiers through the season.
Rain adds support for the Korean won
Rain is adding support for KRW1, the world’s first Korean won stablecoin, issued by BDACS.
Through the partnership, businesses will be able to use KRW1 to power won-denominated stablecoin card programs that work anywhere Visa is accepted.
A new path for the Korean won
For most of its history, the won has been largely a domestic currency. Korea has spent years working to internationalize it.
KRW1 creates a new path. It brings the won onchain, while Rain connects it to the global Visa network.
Cardholders will be able to spend from KRW1-backed balances at more than 175 million Visa merchant locations worldwide. Merchants will see a standard Visa transaction and get paid as they normally would, while Rain handles settlement with Visa in the background.
This creates a new way to build won-denominated card products, including cards for travelers and students abroad, corporate travel and expense programs, and cards tied to KRW1 balances used for creator and contractor payouts.
Built on Rain’s global card infrastructure
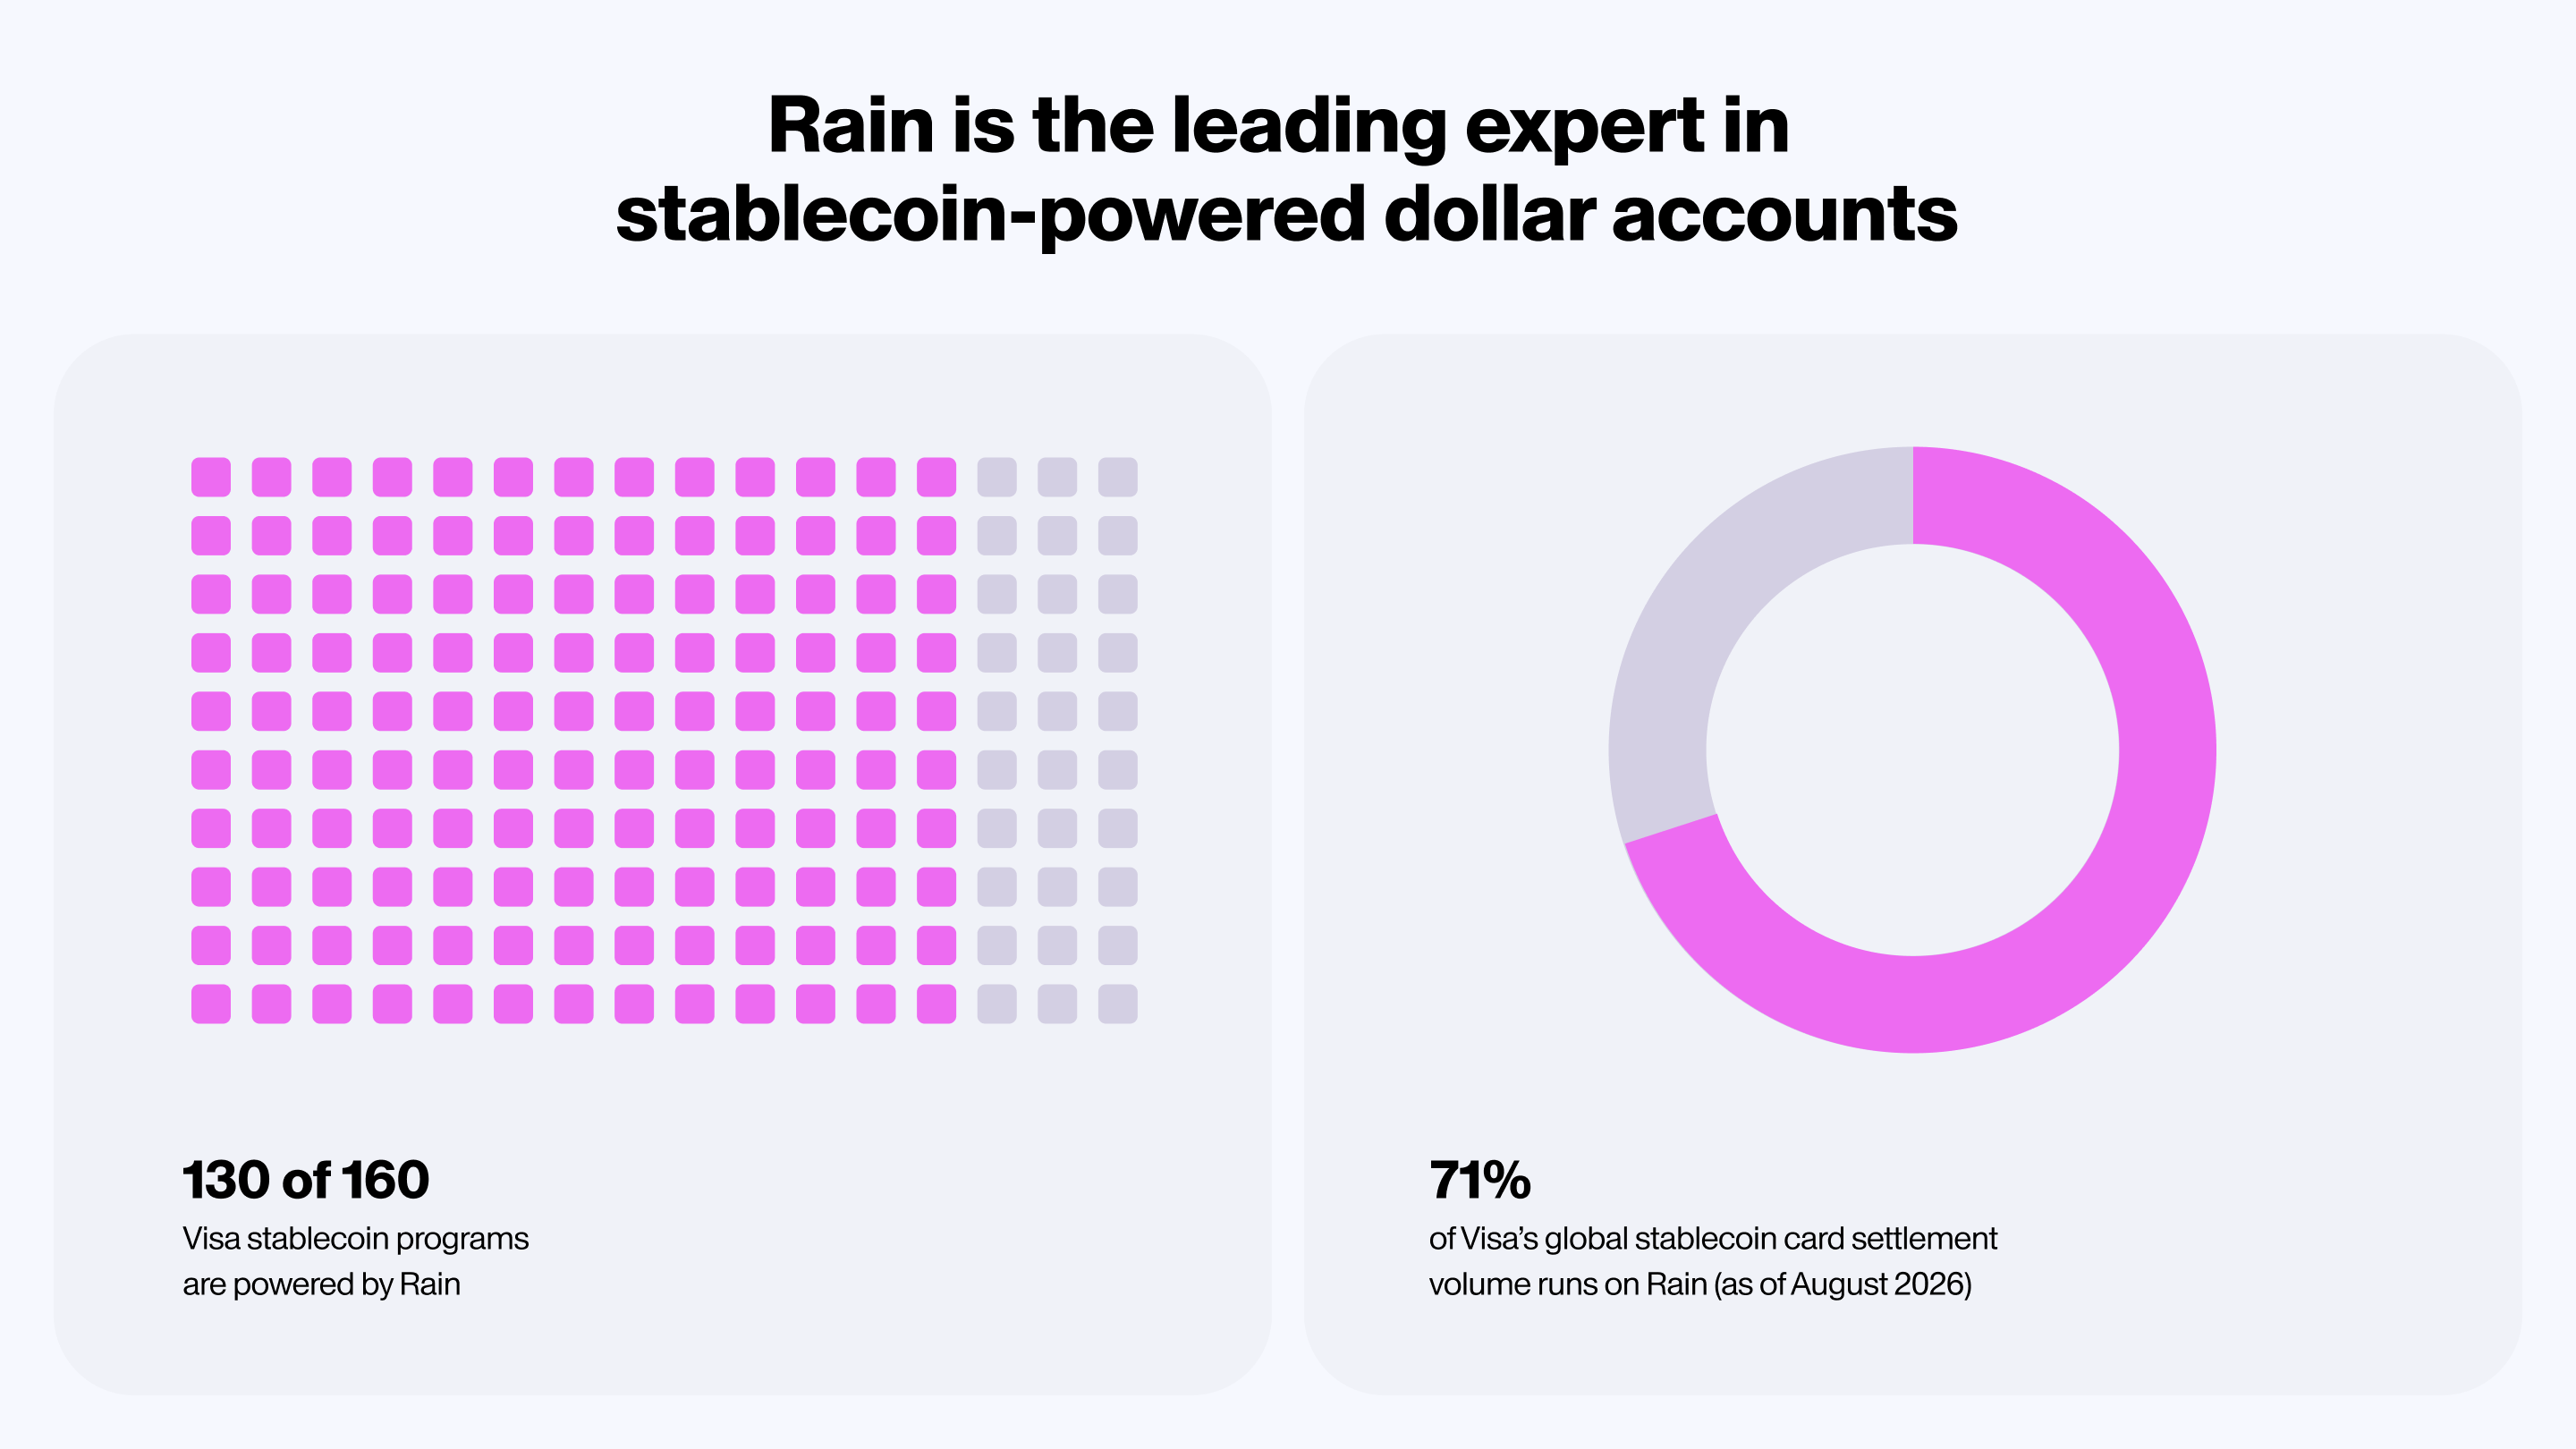
Stablecoin card programs using KRW1 will run on the same infrastructure as Rain’s 130+ live programs.
That means the same capital efficiency from daily settlement, with acceptance at 175M+ Visa merchant locations worldwide.
BDACS issues and custodies KRW1, which is fully backed by won reserves held at Woori Bank. Rain provides the card issuance, program management, and settlement infrastructure.
Together, the infrastructure gives businesses a new, more efficient way to build won-denominated card products for users around the world.
Build with KRW1
Interested in building a won-denominated card program with KRW1?
Rain expands global payouts to more than 80 countries in 50 currencies
Paying people and businesses around the world is still harder than it should be. That’s why Rain built Global Payouts.
With Rain’s newly expanded global payout capabilities, partners can offer international payment services to every kind of customer. From a single stablecoin balance, businesses and consumers can send money to recipients in 50 currencies across more than 80 countries. A company in Germany can send a supplier in South Africa their payment in rand. A marketplace in Mexico can send a seller in the Philippines their earnings in pesos. An individual in the US can send a relative in India remittance payments in rupees.
The funds start as stablecoins, but arrive in local currencies. The recipient never touches stablecoins, and doesn’t have to know they are involved at all.
The mechanics are simple. Rather than prefunding accounts in every local currency, partners cover every market they support from a single stablecoin balance. When a payment is initiated, Rain returns a locked quote with the exchange rate, the cost, and the exact amount that will land in the recipient's account. Once that quote is accepted, Rain returns a deposit address, and the sender funds it with stablecoins. Who that sender is, is the partner's decision. It can be their end user, or it can be the partner itself. The funds then go out as local currency into the recipient's bank account, and status updates flow back through Rain's API at every step.
Traditionally, making these types of payments requires a patchwork of providers. International wire transfers come with intermediary banks and layers of processing fees. These charges are not always locked in ahead of time, so the amount that is received isn’t what was expected, even when the foreign exchange rate was guaranteed. With global payouts from Rain, we have done the hard work of aggregating licensed providers in each market, so the sender can know precisely how much will land before they make the payment. No surprises, no hidden fees.
Businesses that issue international payments typically need to partner with a different payout provider in every market, each requiring its own prefunded account or a local entity. Rain’s global payout infrastructure is different. Instead of prefunding local currency accounts all over the world, partners hold one USDC balance that covers every destination the partner wants to support, so they don’t have to hold capital idle in multiple local currencies.
Global Payouts builds off of Rain’s existing products. Stablecoin cards make stablecoins spendable at more than 175 million merchant locations around the world. Virtual accounts add an onramp layer, letting partners move seamlessly between fiat currencies and stablecoins through named USD accounts. Global Payouts extend that stack by letting partners deliver those funds as local currency around the world.
Global Payouts is live today, with plans to reach 95 countries and more than 60 currencies by the end of the year. If you’re ready to explore what Rain’s payment infrastructure can unlock for your business, let’s talk.
The rules behind rewards programs in the US
In card programs, most people see rewards as the fun part. Designing a loyalty program is like designing a game—you determine the behaviors you want to encourage and engineer the payoff. It’s the step everyone wants to be involved in, especially your lawyers.
Card incentives are arguably your most effective tool for attracting and retaining cardholders. These programs are also among the most heavily regulated features in payments, sitting at a unique intersection of consumer protection, prize promotion law, and financial regulation.
There may be some game theory involved in designing a reward program, but it’s certainly not all fun and games—I know from experience. Before joining Rain, I was a federal prosecutor. I later served as Associate Deputy Attorney General at the Justice Department, and then as Associate Counsel to the President in the White House Counsel's Office. It’s easy to cross a legal line you didn’t realize was there, and rewards programs come with lots of lines.
In this guide, I’ll talk about the rules around rewards programs in the United States at a high level. I'll also share how we built Rain’s native Rewards product and explain the legal review process all Rain programs must complete. The exact laws and regulations depend on the state and specific structure of the offering, so take this as educational and not legal advice.
Deliver what’s advertised
The general principle for rewards programs is the company must to fulfill the promise it makes. Cardholders are told they will receive something in exchange for some behavior—like one point per dollar spent—and when they complete that behavior, they need to be credited.
This falls under consumer protection. Federal law prohibits unfair, deceptive, or abusive practices in connection with consumer financial products, and every state has its own consumer protection statute. The regulators enforcing these laws—the Consumer Financial Protection Bureau (CFPB), the Federal Trade Commission (FTC), and state attorneys general—read a program's marketing copy and its terms as a single document. If the headline says 3% back on everything, the fine print needs to match.
The CFPB made this explicit in Circular 2024-07, issued in December 2024. This policy statement warned that a program operator may violate federal law when it devalues rewards a cardholder has already earned, when it revokes or denies rewards based on conditions that were buried or vague at signup, or when it deducts points without delivering the corresponding benefit.
The circular also addresses a scenario that applies to rewards programs with merchant partners. When a partner drops out of a program, the CFPB expects the operator to take reasonable steps to preserve the value cardholders have accrued, whether by shifting points toward other partners or by allowing a cash-out. For example, if cardholders are told their points can be redeemed with a certain airline, and then that airline stops working with the card program, the cardholders should be given something of relatively equal value. Earned rewards are a liability the program owes its cardholders.
In May 2025, the CFPB withdrew 67 guidance documents in a sweeping rollback, but the circular remains.
Card rewards also intersect with banking regulation, and which rules apply depends on the underlying product. When rewards attach to a credit card, the Truth in Lending Act and Regulation Z govern how the card's terms can be advertised. Certain phrases trigger mandatory disclosures. The Credit Card Accountability Responsibility and Disclosure Act of 2009, known as the CARD Act, added further transparency requirements for how card terms are presented and changed. Debit and prepaid card programs fall under the Electronic Fund Transfer Act and Regulation E, and the disclosure obligations depend on the type of product.
When rewards become a raffle
When a rewards program has an element of chance it moves into prize promotion law. Every state prohibits private lotteries, and generally a program becomes one when it combines three elements: prize, chance, and consideration. Most card rewards programs are deterministic—a behavior (spending) results in a prize (points or cashback). When programs do add in an element of chance the classification can change.
Some examples of this structure are spin-to-win, mystery point drops, and campaigns where one lucky cardholder wins something. If cardholders are required to pay or spend to participate, the promotion now has consideration, which can make it a lottery.
A sweepstakes is a promotion without consideration. This is why you’ll often see "No Purchase Necessary" on sweepstakes advertisements paired with a free way to enter, known as an Alternate Method of Entry, or AMOE. The free path is what keeps a sweepstakes from becoming a lottery, and it has to carry the same odds of winning as the paid entry option. If the free route is hidden, slow, or far less attractive than paying, regulators can decide that consideration effectively exists and treat the whole promotion as unlicensed gambling. A contest takes the opposite approach and removes chance instead of consideration. In this case, winners are judged on skill or merit. An example could be a card program offering a prize to the cardholder who makes the most referrals. Contest entry fees are allowed in many states, but not all.
Sweepstakes carry specific administrative obligations in a few states. New York, Florida, and Rhode Island are the only three with registration requirements (as of the writing of this article). New York requires registration and a surety bond at least 30 days before launch for prize promotions exceeding $5,000 in total value. Sweepstakes operators must also submit a list of winners afterwards. Florida imposes a similar registration and bonding requirement, with a filing due at least seven days before the promotion begins. Rhode Island has the strictest policy, requiring registration without a bond for retail promotions where prizes exceed $500. Many national programs handle this by excluding residents of the registration states or by keeping total prize values under these thresholds.
How we built Rewards from Rain
The rules I described above shaped how we built Rain’s native Rewards product, an optional add-on to any of our card programs. Partners can customize the specific mechanics of their rewards programs, but in every case, terms are always clearly disclosed to the cardholder.
Rewards from Rain does not support sweepstakes or prize draws. Those move a program into prize promotion law and carry the risk of a promotion being classified as an illegal lottery. Rain’s Rewards offering complies with every US rule covered above, and with the rules of every other market where we operate.
Legal review before launch
Any rewards, cashback, or promotional program tied to a Rain card product is reviewed and approved by Rain's legal team before it goes live. That includes deterministic cashback, points tiers, referral incentives, and anything with a prize or chance component.
The same mechanic can be legal in one state and prohibited in the next. It can require a simple filing in one country and months of government authorization in another. It can change legal character entirely based on how entry, odds, and disclosures are structured. Review before launch catches these issues while they are still design questions, when fixing them is much easier.
The best time to involve us is when the program is still being created. Bring the concept to your account manager and to our legal team early, and we'll help you land on a structure that works.
This guide is for general educational purposes and does not constitute legal advice. Promotion laws change frequently and vary by jurisdiction. For any specific program, consult qualified counsel, and for any program tied to a Rain card product, obtain Rain Legal review and approval before launch.
Rain Launches the Agentic Payments Alliance to Guide the Future of Agent-Driven Commerce
Over 25 industry leaders, including Visa, Mastercard, Fiserv, Circle, Solana, and Remitly, join to define the future of agentic commerce
Rain, the enterprise-grade infrastructure for stablecoin-powered payments, today announced the launch of the Agentic Payments Alliance (APA), a coalition of organizations working together to help guide the development of agentic commerce. Founding members include Visa, Mastercard, Fiserv, Circle, Solana, and Remitly.
By 2030, McKinsey projects between $3 trillion and $5 trillion in global agentic commerce. Much of the infrastructure that activity will depend on, including how agents get authorized, how fraud gets caught, and how loyalty and rewards travel with an agent, is still being defined. The APA was formed to bring the people building that infrastructure into the same conversation, before those decisions get made in isolation.
Rain has spent the past year building toward this moment, including its Agent Control Layer and Scoped Cards, which give agents widely accepted payment credentials that are safe and limited. That work put Rain in a position to convene founding members across the industry rather than build the category alone.
The Alliance itself is a working coalition, run collectively by its founding members rather than owned by any one company. Members will set its charter and mission together. Early work is expected to include shared research and frameworks, testing emerging standards for agent identity and authorization, and advocacy on the regulatory questions agentic commerce raises.
Founding members will also get early access to Rain's Agentic Startup Program, an accelerator supporting early-stage companies building for agentic commerce. The program's first cohort of five startups will present at a demo day open to Alliance members, giving founding organizations a direct look at the applications and use cases shaping this category.
“The risk in a moment like this is not that the industry moves too slowly — it's that innovation outpaces alignment,” said Sherri Haymond, executive vice president and global head of Digital Commercialization at Mastercard. “For decades, Mastercard has helped shape the standards that enable commerce at scale, and our participation in the Agentic Payments Alliance is a natural extension of that work for the agentic era.”
“No single company should get to decide how agents transact on someone's behalf. That has to come from the platforms building the rails, the regulators setting the rules, and the innovators closest to how agents are actually being used today,” said Farooq Malik, co-founder and CEO of Rain. “We initiated the Agentic Payments Alliance to put all of these parties in the same room, and to do it now, while the category is still taking shape.”
Founding Members
The Agentic Payments Alliance's founding coalition includes: Avalanche, Basis Theory, Chainalysis, Circle, Coinflow, Crossmint, delta Network, Episode Six, Evertec, Fireblocks, Fiserv, Kala, Lithic, Mastercard, Monad, PayOS, Rain, Remitly, Rialo by Subzero Labs, Sardine, Shift4, Solana, Turnkey, Uniswap Labs, Visa, and Yuno.
How to Join
Organizations across payments, financial services, technology, and policy interested in joining the Agentic Payments Alliance can reach out at apa@rain.xyz.
About Rain
Rain is the global stablecoin payments platform for enterprises, neobanks, platforms, developers, and AI agents. Our technology allows partners to move, store, and use stablecoins instantly and compliantly through global payment cards, rewards, on/offramps, stablecoin and fiat wallets, and cross-border rails. As both a Visa and Mastercard Principal Member, Rain issues cards that work at more than 175 million merchant locations in over 200 countries and territories. Built natively for stablecoins and trusted by more than 100 organizations worldwide, Rain delivers secure, scalable infrastructure that makes money move freely and instantly around the world. Learn more at https://www.rain.xyz/.
Read original press release here: https://www.prnewswire.com/news-releases/rain-launches-the-agentic-payments-alliance-to-guide-the-future-of-agent-driven-commerce-302853532.html
The Anatomy of a Stablecoin Card Swipe
Card networks are a marvel of human coordination.
Every second, they process over 25,000 transactions around the world. Each year, they move over $30 trillion across 800 billion payments.
With a tap or a swipe, you can buy just about anything at 175M+ merchant locations. In person or online.
But while making a card purchase feels instant to you, the systems that actually move money from your account to the merchant are not so simple. They rely on pre-internet financial plumbing that imposes real costs on the companies behind your card. Costs that compound when money needs to cross borders.
While hard for the average person to see, these costs have restricted everyone but the deepest-pocketed companies from offering card services. Even for them, whole populations remain unprofitable to serve.
Here, we'll explain how card networks work, identify their strengths and where they’re showing their age. Then we'll explain how stablecoin cards preserve those strengths, while upgrading antiquated financial plumbing for the modern era.
By the end, you'll understand why stablecoins underlie more and more of the world's $30 trillion in card payments each year.
Authorization: the 2-second miracle
To buy your $5 morning coffee, you tap your card and within two seconds the transaction is approved and you’re on your way.
Unbeknownst to you, that tap sets off a series of messages. From the card reader, to the coffee shop's bank, through the card network, to your card issuer. This process confirms that you can afford the coffee, and that the purchase doesn't look like fraud. An approval then races back along the same path. All in two seconds.
This is where the marvel of the system lies. It lets two strangers, represented by two different institutions, transact in an instant, and then move the money later, according to a set of rules neither of you ever had to think about.
It works billions of times a day, the same in Boston or Bogotá, and everywhere in between.
Interchange: the cost of miracles
To accept your payment, the coffee shop hands over a cut of your $5. In the US, usually around 2-3%.
That 2-3% is split among three different companies. The card network (Visa, Mastercard, etc.) keeps a small sliver. Another sliver goes to the payment processor that the merchant uses to accept the card (Square, Toast, etc.). Then the rest goes to the company that issued the card.
The fee that goes to your card issuer is called interchange.
Interchange is the engine that makes the entire system work. Without it, no business would take on the risk and costs associated with issuing your card. It also funds the rewards you likely enjoy, as many card issuers pass a portion of these fees back to you, in the form of cash back, airline miles, and more.
These fees are the cost of using this complex system that magically authorizes billions of transactions a day. 24/7.
But this two-second approval is only the first part of the story. Moving the actual money takes two steps: clearing, then settlement.
Clearing: the great compression
When your coffee purchase was approved, your card issuer sent a message telling your coffee shop you were good for it. Along with an agreement to send the money later.
No money actually moved.
The first step is called clearing. At the end of the day, the coffee shop's bank bundles your transaction with every other, and submits the list to the card network.
The network takes that list, along with lists from the banks of millions of other merchants, and nets everything out into an even simpler list. One that shows what each bank owes, and what each bank is owed.
Clearing is another marvel of the system. It compresses billions of daily transactions into a short list of IOUs between banks.
However, the next step, where the money actually moves, is where the system is starting to show its age.
Settlement: pre-internet financial plumbing
Settlement is the vast behind-the-scenes machinery that shuffles money from your card issuer to the coffee shop's bank. Plus about $80 billion more from every other purchase that day.
Money moves not one coffee at a time, but in massive, netted batches. Banks that owe pay the card network. Then the network pays the banks that are owed. This is effectively when your coffee shop gets paid.
On a debit card, it comes straight out of your account. On a credit card, your card issuer fronts it, and collects from you at a later date.
The system works well enough. You’ve long finished your coffee by this point, and the coffee shop gets paid eventually.
The challenge sits with the company behind your card. It has to make sure it always has enough money on hand when these settlement batches come due. For your coffee purchase, and for the purchases of every other customer it serves.
And it has to do so through systems built in a pre-internet world.
These systems produce lags, which is where the first big problem appears.
Prefunding: the cost of waiting
Settlement runs on bank time.
In the US, most settlement moves through two systems: ACH and Fedwire. One built in the 1970s, the other with roots in 1918. Neither runs on nights, weekends or holidays.
So if you bought your coffee Friday at 5:30pm, the money won’t move to the merchant until Monday morning. Tuesday if it’s a long holiday weekend. And this lag is where the system’s first hidden tax shows up. Not for you or the coffee shop, but for your card issuer.
Your issuer has to be ready to pay for your $5 coffee, and every other transaction from that weekend. Let’s say its customers spend $1M a day, and Monday is a holiday. It’ll need $4M sitting in an account by Friday night waiting to move Tuesday morning.
That idle money waiting for settlement is called prefunding. It's money the card issuer could be using for working capital, or reinvesting in its business. Instead it just sits there, waiting for pre-internet financial plumbing to kick in during banking hours.
Now imagine your card issuer needs to settle $10M or $100M a day. Then it becomes $40M or $400M in idle capital.
There's no fundamental reason it needs to work like this, other than the fact that these settlement systems are heavily entrenched. It's why, historically, card programs could only be run by banks with pockets deep enough to leave that kind of money sitting idle. And it leaves less room for smaller, more nimble issuers.
Cross-border: where the pipes end
Up until now, we've focused on a single US domestic transaction.
One country, one currency, one holiday calendar.
Now imagine you live in Colombia, spending pesos on a card issued locally. You can buy your coffee in Bogotá with the same two-second approval, and your card issuer runs into the same prefunding expense.
What if you buy a Claude subscription online from Anthropic (a US company)? For you, nothing changes. You tap and pay in pesos. But for a cross-border transaction like this, the network must be paid in dollars. Your card issuer now owes a currency it doesn't hold.
US dollar settlement systems (ACH and Fedwire) are only available to US banks. So your card issuer has to do what nearly everyone outside the US does. It opens an account at a bank in New York, converts pesos to dollars, and prefunds it. That bank then settles US dollar transactions on its behalf.
Opening that account takes months of compliance reviews. Funding it takes an FX trade, which takes a spread. And the instructions to move the money travel over SWIFT, a bank messaging network founded in 1973.
This daisy-chain of banks holding money for other banks is called the correspondent banking system.
And it means your card issuer now runs prefunding twice. One pot of idle pesos in Bogotá. One pot of idle dollars in New York. Two holiday calendars to manage.
If your card issuer wants to serve users in Mexico, Argentina, and Europe, it gets more complicated. Each new market means another local bank willing to hold its money, more FX spreads to pay, and more idle capital to lock up. Three more pots, five in all, scattered around the world.
Serving a global audience takes even deeper pockets and a ton of patience. For businesses born on the internet, whose users show up from everywhere on day one, it's a structural mismatch. Global companies are forced into geographic borders.
Enter stablecoins
Stablecoins emerged in 2014, originally as a way to trade in and out of cryptocurrencies like Bitcoin.
They move over blockchains, which are essentially a new kind of database that runs 24/7, 365. Stablecoin issuers back these digital dollars with liquid assets, mostly US Treasuries. As long as each one can be redeemed for a dollar in the banking system, they hold their value at $1.
Stablecoins soon grew popular in emerging markets. Especially among people who wanted the stability of dollars but couldn't get dollar bank accounts.
While having clear advantages over traditional dollars, mainly that they move 24/7 at little cost to anyone with an internet connection, they weren't ready for mainstream adoption. They were technically complex to use, and nearly impossible for merchants to accept.
Enter stablecoin cards
The first stablecoin cards appeared in 2019. They let you spend stablecoins anywhere cards were accepted. But the card issuer simply sold your stablecoins for ordinary dollars and settled with the card networks the old-fashioned way.
The companies behind the card still had to prefund ordinary dollars in a bank account, settle on bank time, through every pre-internet pipe described above. Same as before.
None of the settlement bottlenecks were addressed. They just bolted stablecoins onto the old system.
Enter stablecoin settlement
Then in 2021, Visa became the first major network to accept a stablecoin for settlement.
Visa began letting card issuers settle in USDC, a popular stablecoin, directly with the Visa network. And since blockchains aren't tethered to legacy banking hours, Visa eventually enabled settlement 365 days a year. Mastercard followed suit.
For merchants, nothing changed. They still got paid out by the card network in their local currency. But this back office upgrade changed the game for the companies behind your card.
Daily settlement eliminated the need to park millions to account for multi-day lags. A single pot of stablecoin collateral could now serve a global audience, breaking reliance on the correspondent banking system.
Serving the world no longer required a banking empire.
Anatomy of a stablecoin card swipe
Let's return to your original $5 coffee purchase. Nothing about the experience changes for you or the coffee shop.
You tap your card or your phone. The same message races from the coffee shop's bank, through the card network, to the company behind your card. The only difference is what it's checking: that you have enough spending power onchain, rather than in a bank account.
The answer comes back along the same path. You're good for it, and it doesn't look like fraud. Two seconds, approved.
The coffee shop hands over its 2-3% fee, split the same three ways. Your rewards still get funded. At the end of the day, your purchase lands on the netted list alongside hundreds of millions of others. That list tells your card company exactly what it owes the network.
Everything from the tap through clearing runs exactly as it always has.
The difference comes when it's time for settlement. The multi-day prefunding pile-up vanishes. Instead, the company behind your card sends the network one lump daily payment in stablecoins, covering your coffee and everything else its customers bought that day.
It can make that payment any day of the year. On a Saturday. On Christmas morning. The network then pays out the merchant banks in regular currency. The same as it always has.
Prefunding, revisited
Recall your Friday evening coffee purchase heading into a holiday weekend. Your card program settling $1M a day no longer has to park $4M to wait for Fedwire and ACH to open Tuesday morning.
Friday's bill gets paid Friday. Saturday's gets paid Saturday. Most of that $4M stays in the program's hands every weekend. More as it scales.
That money goes back to work, funding growth, product, and payroll. Every card program becomes more profitable to run. So more companies launch branded cards, and existing programs expand into markets that never made economic sense before.
The net result is access to more financial services for more people.
Cross-border, revisited
Fly back to Bogotá. Now your card is backed by digital dollars, rather than pesos.
Like many in Latin America, you're happy to save in US dollars. You can buy your local coffee, and your coffee shop can still get paid in pesos through the card network. And you can buy your Claude or ChatGPT subscription just the same.
The difference for the company behind your card is huge. It no longer needs separate idle pots of pesos and dollars sitting in Bogotá and New York. Every bill from the network is due in dollars, and your coffee and Claude subscription are paid from the same stablecoin balance.
This eliminates the need to set up a banking relationship in New York. No FX trade to fund it, no spread to pay. No SWIFT instructions to send.
Similarly, expansion to Mexico, Argentina, and Europe no longer requires a local bank to hold its money, or new holiday calendars to manage. Every new market settles daily from the same wallet. Five pots of idle capital become one.
For a card program, the correspondent banking system just became optional.
Anatomy of Rain
So far, we've walked through how the card networks work, and how stablecoin settlement upgrades the plumbing underneath them.
Rain is the company that pioneered this new breed of card. It provides a single platform for launching a stablecoin card, and for every stablecoin service around it. Rain holds principal memberships with Visa and Mastercard and settles directly with the networks in stablecoins, every day of the year. It was the first company in history to settle with Visa over a weekend and on Christmas.
Financial institutions, neobanks, and technology platforms use Rain to launch stablecoin card programs because they're cheaper and easier than traditional cards. The programs are also able to launch in multiple jurisdictions at once, with no correspondent bank accounts to open and no idle pots to fund.
From there, they can layer on rewards, embedded wallets, and 24/7 cross-border transfers.
Programs built on Rain carry the same compliance obligations as any traditional card program. This includes know-your-customer checks, fraud monitoring, and transaction monitoring.
Who's building on stablecoin cards
Companies big and small are launching stablecoin cards, creating new financial services that weren’t viable before.
There’s a new class of neobanks focused on narrow markets they know best, like the many teams across Latin America offering dollar accounts to users the banks never served. Internet marketplaces are putting cards in the hands of a global user base without dealing with a patchwork of correspondent banks.
Established institutions that could afford the old way of doing business are finding it cheaper to run on the new one. Like the world's largest remittance company, now sending stablecoins straight to the recipient's phone, spendable through an embedded Rain card the moment they land.
Stablecoin cards make up a small share of card payments today, but judging by who's building on them, that won't be true for long.
The invisible upgrade
You've likely never thought about the authorization, clearing, and settlement systems that transfer your $5 to your coffee shop. Nor should you have to. The same is true with stablecoin cards. They just work, without the average person ever noticing anything has changed.
What people will notice is financial services becoming more abundant. That more companies are able to offer them. And that more institutions are serving people who were never profitable to serve before.
Stablecoin cards have rebuilt settlement from first principles. The rest of the card stack comes next. The messaging protocol behind each swipe still runs on a standard from 1987 and is due for an upgrade. Merchants will increasingly want to be paid out in stablecoins directly. And AI agents will transact with each other in stablecoins, using cards to touch the real economy.
Most importantly, stablecoin cards have made stablecoins compatible with the existing financial system. Famously, mobile phones first had to work with landlines before becoming the standard and producing innovations no one predicted. We expect stablecoins to do the same.
This is where the world is headed. The upgrade is already well underway.
Thanks & further reading
This piece borrows its title, with permission, from Ahmed Siddiqui's The Anatomy of the Swipe, which explains how money moves when you tap a card. His sequel, The Evolution of the Swipe, is out now.
For more on the gap between authorization and settlement, read Alex Johnson's The Message and the Money.
Thanks to Farooq Malik, Charles Yoo-Naut, Lucas Piazza, Sean Clark, Casey Wagner, and Sophia Goldberg for informing and reviewing this piece. And to Hilda Wong for the great design work.
Behind the buy: building Rain's stored value layer with Ansa
Rain powers the full flow of money, including card issuing, embedded wallets, and money movement, through a single platform. A key part of our product strategy is to give partners a permanent place in their customers' routines, where every purchase strengthens the relationship instead of ending it.
Today, Rain is announcing its acquisition of Ansa, a platform built for branded stored value and closed-loop payments, and we're welcoming their team as the newest Rainmakers.
"Every great merchant or consumer brand eventually wants their own version of the Starbucks wallet, but very few have the infrastructure to pull it off," said Sophia Goldberg, Ansa's founder, who is joining Rain as Head of Payments. "Bringing that expertise onto Rain's platform means partners can offer their customers a branded app with spending power, rewards, and a card that works across multiple locations, all in one place."
Why stored value matters
Stored value isn't a new idea. Starbucks proved over a decade ago that a well-designed branded wallet can become one of a company's most valuable assets, holding well over a billion dollars in customer balances and turning routine purchases into daily habits. Few brands have matched that model since, mostly because the infrastructure behind it, POS integrations, incentive tooling, reconciliation, fraud controls, redemption across app, web, and in-store, has been expensive and slow to build from scratch.
Ansa built that infrastructure so any merchant could offer a version of the same experience. A prefunded wallet keeps everyday spend inside a brand's own ecosystem, and incentives with built-in expiration turn a one-time reward into a reason to come back this week rather than sometime next quarter. Programs built this way tend to follow a familiar pattern, with customers visiting more often, spending more per visit, and costing less to serve.
Ansa built on rails that merchants already use
Stored value sounds great to a merchant right up until they ask how customers actually pay with it in-store. Most merchants already have a point-of-sale system they like, and asking them to rip it out or bolt on new hardware is where these programs usually die. Ansa solved that problem, and it's where their real innovation happened.
Ansa struck a truly novel arrangement with Mastercard that let a stored balance spend in-store over Mastercard's own rails, using the exact same terminal a merchant already had. If a merchant already accepted Mastercard, they could accept an Ansa-powered wallet without touching their hardware or software at all. Online and in-app, the experience worked differently. Instead of riding a card network, the transaction would ping Ansa's API directly for authorization.
That solved a real problem, but it was still a closed-loop program by design. A cardholder could spend their stored balance at the merchant who issued it, and nowhere else. Now that Ansa is part of Rain, that changes. Paired with Rain's own work as a Mastercard Principal Member and Visa issuer, partners will be able to extend a stored balance beyond a single merchant's own registers, accepted on both Visa and Mastercard rails at participating business.
New experiences for partners
This isn't the first time we've added a layer to Rain's platform to unlock experiences partners couldn't build on their own. In 2025, Rain acquired Uptop, bringing card-linked rewards to sports and entertainment, powering programs for fans of the Cleveland Cavaliers, the Detroit Pistons, LSU athletics, and more.
Ansa's stored value and incentive tooling adds another dimension to that vision, and now that Ansa is part of Rain, it can go further than a single merchant. Picture a team or venue giving fans a branded wallet loaded with credits for concessions and merch, rewards that show up automatically when they spend, and a card that works at the venue and, thanks to Rain's own Visa and Mastercard relationships, at the restaurants and bars around it too, so a fan's night doesn't have to end at the gate.
But it's more than just sports and entertainment. A hotel brand could give guests a reloadable balance that covers everything from the minibar to a future stay. A cruise line could put a single onboard wallet in every passenger's hand, good at every bar, shop, and excursion desk on the ship. A theme park could load a family's tickets, food credits, and merchandise budget onto one card that taps at every gate and register. In each case, a branded wallet holds credits and rewards that are spendable everywhere the brand's customers already are, on a card that can be easily configured for purchases at a wide range of merchants that accept Visa and Mastercard.
A glimpse at what's next: agentic payments
Rain has been building toward a future where agents transact as capably and safely as people do. Scoped cards and controlled agentic payments already give an AI agent a tightly bounded budget to spend on someone's behalf, rather than an uncapped balance, the same principle behind a spending balance scoped to specific restaurants around an arena, just aimed at agents instead of fans. That foundation rests on the same core capability Ansa has spent years perfecting, a programmable balance with rules attached that governs who can spend it, where, how much, and for how long before it expires.
Ansa's team has built and hardened that kind of programmable, rules-based balance at scale, today for people rather than agents. As agentic commerce moves from concept to production, that experience gives Rain a real head start. Sophia will have a direct hand in shaping this work, and we'll share more on where it goes in the months ahead.
The founder behind Ansa
Ansa was founded and led by Sophia Goldberg, who is joining Rain as Head of Payments. She spent several years at Adyen managing global accounts and product before founding Ansa, and along the way wrote The Field Guide to Global Payments, a widely read book on how money moves around the world. American Banker named her one of its Innovators of the Year in 2024, and QSR Magazine and NYC Fintech Women have recognized her work as well. At Rain, she'll lead payments strategy with a front-row seat to both the stored value work described above and what comes next in agentic commerce.
Looking ahead
Card issuing makes money spendable. Stored value is what keeps that spend inside a brand's own ecosystem, turning a single purchase into a habit and a habit into loyalty, all without asking customers to give up the acceptance they expect from modern payments. Bringing Ansa's team and technology into Rain gives partners a way to build all of that from a single platform.
We're excited to welcome the Ansa team to Rain, and even more excited about the kinds of programs our partners will be able to build with embedded wallets, rewards, and stablecoins working together.
If you're building a program where you want your customers' funds, and their loyalty, to stay inside your ecosystem, we'd love to talk.
How Rain approaches wallet monitoring: Q&A with Chainalysis
At Rain, fraud prevention and detection starts long before a user attempts a transaction. One of the earliest tools we use to mitigate risk is wallet monitoring, the practice of screening where onchain value has been before arriving in a smart contract connected to a Rain-powered product. Identifying source of funds is one of the primary ways we protect the platform, our partners, and our users.
Screening at this level takes overlapping systems and specialized expertise, which is why we work with best-in-class vendors alongside our internal controls. One of these partners is blockchain analytics company Chainalysis. We sat down with Caitlin Barnett, Director of Regulation and Compliance at Chainalysis, to dig into how upstream wallets are identified and risk-scored, and why real-time monitoring is mission critical for stablecoin payment infrastructure providers like Rain.
Q: How does Chainalysis identify wallets onchain?
A: It starts with clustering, which is the process of grouping individual blockchain addresses that we can determine are controlled by the same entity. The scientific methods for grouping addresses together depend on the blockchain. On UTXO chains like Bitcoin, we use co-spend heuristics. If two addresses sign the same transaction as inputs, they share a private key and therefore belong to the same wallet. On account-based chains like Ethereum or Tron, different techniques apply, but the principle is the same and the end goal is to link addresses to their common owner. Importantly, we only leverage Machine Learning techniques for lead generation as those are probabilistic and less certain.
Once we have clusters, we layer on attribution. Our research team continuously maps clusters to real-world identities through Open-Source Intelligence (OSINT) research, law enforcement partnerships, proprietary data collection, and community submissions. That means a cluster isn't just "these 50 addresses move funds together," it's "these 50 addresses belong to VASP ABC," or "this cluster is operated by a sanctioned entity."
We also maintain address-level identifications for cases where a single address within a larger cluster has a distinct designation. For example, for a specific deposit address at a major exchange that's been listed on an OFAC sanctions designation, the parent cluster might be a legitimate exchange, but that particular address carries its own risk signal.
The result is a layered identification system: clustering tells you who controls what, attribution tells you who they are, and address-level identifications distinguish operators from users.
Q: How does Chainalysis identify risky actors?
A: We assess risk through two complementary lenses: direct identification and exposure analysis.
Direct identification is the most straightforward. If we've attributed a cluster to a known ransomware group, a sanctioned entity, a darknet marketplace, or a scam operation, that identification carries an inherent risk category. Our research team tracks these entities continuously and maintains the most comprehensive high quality database of illicit actor attributions in the industry.
Exposure analysis is where things get more nuanced. Even if a wallet doesn't belong to a known bad actor, it may have significant transactional ties to one. We analyze both direct exposure (the wallet transacted directly with a risky counterparty) and indirect exposure (funds passed through intermediaries before reaching the wallet). We break this down by risk category (sanctioned entities, stolen funds, ransomware, darknet markets, fraud shops, child exploitation material, terrorist financing, and others) and quantify it in both percentage and dollar-value terms.
On top of that, our software lets clients set custom alert rules with configurable thresholds so that a transfer triggering, say, 5% indirect exposure to a sanctioned entity fires a high-severity alert, while 1% exposure to a mixing service might be a medium. Risk isn't binary, it's a spectrum, and we give our clients the tools to define where their lines are.
Q: Why is wallet monitoring especially critical for a stablecoin payments provider like Rain?
A: Stablecoins have moved well past crypto-native use. They're now processing real payment volume: cross-border settlement, card transactions, treasury flows. That shift is exactly why regulators hold infrastructure providers to the same standard as any payments processor or money transmitter.
These regulators expect real-time monitoring, not after-the-fact reviews. A payments infrastructure provider sees the transaction as it happens, not weeks later in a batch report. If a sanctioned wallet moves funds through your platform in real time and you don't catch it, that's not a reporting gap you can close later. It's a live compliance failure, and potentially an enforcement action.
Reputation follows directly from that. A payments platform's value depends on partners, banks, and regulators trusting that every transaction moving through it has been screened, not sampled after the fact. Wallet monitoring is how stablecoin platforms demonstrate that trust is earned in real time, transaction by transaction, rather than assumed.
Q: How does wallet monitoring evolve as new chains, wallets, or laundering techniques emerge?
A: This is one of the hardest problems in the space, and honestly, it's a never-ending arms race. A few things are critical to staying ahead.
As the blockchain ecosystem grows and activity expands across an increasing number of networks, Chainalysis coverage must continuously evolve to meet customers wherever onchain activity takes place. Today, Chainalysis supports more than 30 blockchains with deep attribution and clustering coverage, supporting 3-5 new chains each quarter. Supporting a new network goes beyond technical integration and tracking value transfers. We apply existing intelligence, develop new clustering heuristics, and discover new attributions to identify the entities and types of activity occurring onchain. This gives customers the context they need to understand not just how value moves, but who is involved and what that activity represents. This is to say we're constantly onboarding new networks and deepening our analytics on existing ones.
Laundering techniques evolve constantly. Cross-chain bridges, privacy protocols, chain-hopping through DEXs, nested services with the playbook changing every few months. Our response is multi-layered: we invest in cross-chain tracing capabilities so that moving funds from Ethereum to Tron to Solana doesn't break the trail; we deploy threat detection that can flag exploit patterns and anomalous behavior even before a cluster is formally attributed; and we maintain real-time monitoring infrastructure that watches for onchain events such as fund movements, approval changes, and contract interactions at the block level.
Every new attribution, every new cluster identification, and many law enforcement cases we support feed back into the system. The compounding effect of this intelligence network is what makes monitoring more effective over time even as adversaries adapt.
Q: From your vantage point across many clients, what separates a company with a strong wallet monitoring program from one with a weak one?
A: Three things stand out consistently.
First, strong programs are proactive, not reactive. Weak programs screen a wallet when a compliance officer gets a tip or when a regulator asks a question. Strong programs screen in real time every counterparty at the point of transaction whether that's deposits or withdrawals. They also have automated alert pipelines that surface risk without waiting for a human to go looking. The difference between catching a sanctioned entity's funds before they clear versus three days later is the difference between a compliance success and an incident report.
Second, strong programs invest in tuning. Out-of-the-box alert thresholds are a starting point, not a destination. The best teams iterate on their rules by adjusting exposure thresholds by category and building tiered escalation workflows. They understand that 2% indirect exposure to a mixing service means something very different from 2% direct exposure to a sanctioned entity, and their rules reflect that nuance. Weak programs leave default settings in place and drown in noise, which leads to alert fatigue and, eventually, missed real risk.
Third, strong programs treat monitoring as cross-functional, not siloed. The best clients connect their wallet monitoring data to their broader risk and investigation workflows, which allows them to tie blockchain analytics to KYC data, case management, and regulatory reporting. They use exposure data not just to block or allow a transaction, but to understand the full risk profile of a customer relationship over time. A single suspicious transfer is data; the pattern across six months of transfers is intelligence. The companies that build that connective tissue between monitoring and decision-making are the ones that consistently stay ahead of both illicit actors and regulators.
Wallet monitoring is one piece of a larger system
Real-time screening catches what a transaction looks like the moment it happens. But a strong risk program has to hold that same standard at every other point in a payment program's lifecycle: who signs up, where they're signing up from, what changes as a relationship evolves. That's why Rain treats risk mitigation as a continuous discipline rather than a checkpoint, with clear ownership over transaction-level controls, AML and fraud risk assessment, and geographic and sanctions screening from onboarding through ongoing use.
Read more about how we structure that program in How Rain Reduces Risk: A Guide.
How Rain approaches transaction monitoring
At Rain, we monitor every single transaction that runs on our infrastructure. We screen in real-time at the authorization level, and continue reviewing payment activity as it accumulates. That coverage is the foundation of our broader fraud prevention and detection program built to protect the people and businesses who rely on our products.
Transaction monitoring systems are both the least visible and most important parts of a payments company. In the sections that follow we share information about the shape of our transaction monitoring program and the thinking behind it. We do this because openness and transparency are core to our overall approach to compliance, though of course we can’t share all the details because doing so might provide too clear a roadmap to those who might try to circumvent them.
Layered by design
Our approach to fraud prevention and detection is layered by design, because no single control catches everything. Consider how office buildings are protected. The badge reader at the entrance turns away anyone without credentials. The security officer that knows the staff catches the person who has a badge but does not belong. One is a fixed rule and the other is an awareness of what normal looks like, and removing either weakens the whole. Payments security is no different.
Transaction monitoring really starts before a Rain-powered program is even up and running. Our extensive Know Your Business (KYB) screening process helps us establish a baseline for normal program activity, including where transactions will be taking place and what payment volume will look like. Through Know Your Customer (KYC) screening, we collect cardholder details like occupation and address, information that enables us to paint an even more detailed picture of what we should expect from individuals in a program.
Activity that is normal for one program could be suspicious for another, so a single rulebook is ineffective. Picture a corporate travel program next to a payroll card program. In the first, purchases across three countries in a single week look routine. In the second, that same pattern raises red flags. Understanding each program is what allows us to spot genuinely unusual activity without turning away legitimate spending.
The next layer is at the authorization level, in the seconds between a card being presented and a purchase being approved. We monitor card activity in real-time, often catching suspicious activity as soon as a bad actor initiates it. This allows us to reject a fraudulent purchase before it even clears.
When it comes to authorization level declines, some rules are constant and apply to every program that runs on Rain. Transactions tied to sanctioned or restricted jurisdictions will always be declined, as will purchase attempts from blocked merchant categories. When spending breaks the velocity limits for a given card, merchant, or merchant category, we decline transactions. This is one of the most effective defenses against card testing and rapid-fire attacks where a bad actor will run many small charges in quick succession to find out which stolen numbers still work. Catching that burst early makes a real difference. Enhanced, custom controls can be added on top of the ones Rain requires to fit an individual program’s specific risk profile.
The next layer looks beyond any single payment. Once a transaction clears, we keep analyzing activity across the program to catch systemic risks. A group of transactions that each seemed ordinary at authorization can reveal a coordinated scheme when viewed together, and we cannot see that pattern unless we continue to monitor after settlement. Post-transaction monitoring also includes tracking disputes, refunds, and chargebacks to identify fraudulent activity. This layer is important when it comes to tracking fraud rates and the effectiveness of the entire transaction monitoring system.
These layers each work alongside network-level controls and transaction monitoring. The card networks decline transactions their models flag as unauthorized, and they intervene against patterns like BIN attacks, where fraudsters generate and test card numbers at scale.
The controls described in this section are only part of a broader program. We layer in additional rules and dynamic risk signals that adjust as behavior and threats change, and we work to anticipate new attacks rather than react to them.
Where people come in
Not everything resolves in an automated rule, and it shouldn't. When activity trips our monitoring, it goes to human review. Analysts investigate the context around it, and cases that warrant it are escalated to our Compliance team, where we make the final decisions and fulfill our reporting obligations. Automation gives the program its reach, but our skilled people give it judgment.
The honest reality of this work is that it’s never finished. Threats constantly evolve, and a program that is effective today will be tested by something new tomorrow. Our rules and risk signals adjust as behavior changes, and we devote time to studying attack patterns that have not reached us yet. Some of the controls I am proudest of were built for attacks we anticipated before they were attempted.
Transaction monitoring is just one part of a larger system. The KYB and KYC programs I mentioned above and our intensive wallet screening program are described in more detail in our guide on how Rain reduces risk. Together, each part of our risk mitigation program reflects a belief we hold across Rain. In payments, trust is the product and it has to be engineered and defended every day.
A closer look at scoped cards
Payment relationships are built on trust. Whenever you delegate spending, whether it be to an employee, contractor, vendor, or AI agent, you have to decide how much power to hand over. That choice has usually been all or nothing. You share full payment credentials and hope they're used the way you intended, or you hold them back and slow the work down.
That's why Rain developed scoped cards, making it possible to define exactly what a card can do before it's issued. Limits on spend, where the card works, and how long it’s valid are programmed into the card, creating real buying power within set boundaries.
How it works
Partners can design customized payment experiences with Rain's scoped cards offering. Scoped cards work for any situation where a person needs to delegate spending power. An expense platform can give distributed teams cards limited to travel or software. A bill-pay platform can generate a card that only works to pay specific invoices. An automated shopping platform can enable agents to initiate and execute transactions on behalf of humans.
Whatever the use case, scoped cards are the building blocks. The demo below shows just one way a partner could use scoped cards to power purchases. Click through to see the full flow in action.
The rules are set before each card is issued, and parameters can be mixed and matched across cards. A card can carry a maximum transaction amount, work only within approved merchant categories or at specific merchants, and expire after a set date. Cards could be designed to retire after a single purchase, stay active until a one-time budget is met, or refresh on a recurring budget. Each parameter is a capability, allowing cardholders to tailor the payment method to exactly what they need.
Partners can customize controls like the number of active cards a cardholder can have and daily spend limits to fit their program needs. Before a scoped card is issued, each cardholder completes KYC, the same identity verification that sits behind all of Rain’s card programs.
If you're ready to build scoped cards into your product and put precise spending controls in your users' hands, let's talk.
Behind the buy: securing Rain’s onchain stack with Guardrail
At Rain, we’ve long held the view that security has to scale ahead of the business, not chase it.
That conviction has shaped where Rain has invested our engineering efforts, both internally and through our partnerships. A security layer has to detect threats as they happen and intervene before damage is done, and it has to do so consistently across every chain Rain operates on. The teams capable of designing and running a system like that are rare, and Guardrail is one of them.
Guardrail is the proactive, programmable security engine monitoring transactions across 30+ chains and protecting over $30 billion in assets for customers to-date. One of these customers has been Rain. Now, Rain is bringing Guardrail’s technology and team in-house to further extend real-time protection into Rain's products.
“The product is exceptional, but the team is the real reason this matters,” Rain Co-founder Charles Yoo-Naut said. “You can't put together this kind of expertise through individual hires. Samridh has assembled one of the very few groups in the world operating at that depth, and we're fortunate to have them at Rain."
Why runtime security matters
Guardrail is unique in that it defends protocols after deployment, not just before. Most security work in the blockchain industry has focused on pre-deployment audits, which are necessary but unable to catch what happens once contracts are live, where exploits move fast and often use techniques no static review can anticipate. Guardrail closes that gap with continuous runtime monitoring and automated response.
The platform works as a security engine at the base layer of every transaction. Guardrail’s AI model scores each sender, recipient, and smart contract in real time to evaluate signals like transaction value, volume patterns, approval anomalies, and oracle deviations, and then responds in under 100 milliseconds. When something looks wrong, configurable circuit breakers can halt activity before funds move. Attackers typically count on going undetected for hours, but Guardrail closes that window to near zero.
Why this matters now
This work has never been more critical. AI has changed what attackers are capable of, letting them surface exploits faster and adapt their attacks in ways defenders working with manual processes cannot match. Defending a platform like Rain against that requires the kind of continuous, automated security Guardrail has spent the past few years honing.
“We built Guardrail because the biggest unprotected surface in onchain finance isn't the code itself, it's everything that happens after it ships. More than 90% of last year's $3.4B in onchain theft hit code that had already been audited,” Guardrail Founder Samridh Saluja said. “Joining Rain takes that runtime defense to a global stablecoin payments platform where it can have outsized impact.”
What changes for Rain and its partners
By transitioning Guardrail from a vendor to an owned infrastructure layer, the enterprises who depend on Rain get a more resilient and deeply integrated service. That means runtime security scanning every transaction across all the chains Rain operates on, normalizing detection and response regardless of whether a given chain settles in milliseconds or minutes.
Ownership also compresses the time between detection and fix. When security is a vendor relationship, every iteration cycle — identifying a new attack pattern, developing a response, testing and deploying it — has to cross organizational boundaries. With Guardrail embedded inside Rain, those loops run faster and are tuned specifically for the demands of stablecoin payment flows, where the threat surface looks different than in general DeFi.
The data advantage matters too. Running Guardrail on Rain's full transaction volume gives it cross-chain context no outside vendor can accumulate. The per-contract and per-counterparty baselines sharpen with every transaction Rain processes, and that means the protection compounds as Rain scales, rather than staying static.
Rain has operated at the frontier of stablecoin payments since day one, and as that frontier expands, so does the responsibility to protect it. Bringing Guardrail in-house is the natural next step of the conviction Rain has held from the start — security has to be built into the foundation, not bolted on after the fact.
For the enterprises, neobanks, and platforms that depend on Rain, that means every transaction across every chain and every market is protected by a security layer that gets sharper over time. As Rain grows, so does Guardrail's ability to defend it.
Looking ahead
Stablecoins are already moving billions, and the bar for production-grade security is moving up with them. The enterprises building on this rail will only commit if the infrastructure underneath can defend itself in real time.
Bringing Guardrail in-house lets Rain extend that protection as the platform grows, across new chains, new partners, and new categories of stablecoin commerce. We're excited to welcome the Guardrail team and to keep building toward a payments platform where security is part of the foundation, not bolted on top.
If you're building on stablecoins and want security designed right from the start, we'd love to work with you. Please get in touch here.
Introducing Rewards
A card on its own doesn't earn loyalty; people need a reason to keep reaching for it, and the programs that grow are those that give them one. That part isn't new, but what's been missing is a way to build rewards into a card program without the usual mess of vendors and reconciliation.
So we built it ourselves. Today Rain is rolling out Rewards, allowing partners to add a fully-branded, integrated loyalty platform to their card program. This means no separate vendors to piece together or infrastructure to build out, while still being customizable.
In the US, 90% of credit card spend happens on rewards cards, but for many programs, running a rewards layer is out of reach. Loyalty usually meant bringing on a separate vendor, with its own ledger and portal, then wiring it into the card and reconciling the two against each other on a delay. It's expensive, and stitching it together often takes months. Programs that would have benefited from a rewards layer just went without.
With Rain, the rewards live in the same place as everything else. Points, earn rules, and redemption all run on the infrastructure that already handles spend and settlement, so there's no second ledger to keep in sync and no extra vendor in the middle. The points themselves are minted onchain after a transaction has settled. This means every point has a clean record, sitting in the same system that already holds the cardholder's other assets.
Everything else is the partner’s to shape. They set their own earn rules, whether that's a flat rate across the board or extra points in the categories their cardholders care about most, with room to layer in merchant-specific campaigns whenever it makes sense. Cardholders see the partner's brand, not ours, the whole way through. And when they're ready to redeem, they do it right inside the same app, either as credit against their statement or toward hotels and flights in a white-labeled travel portal. Click through the demo below to see how the integrated rewards platform could look.
We’re opening up Rewards to all partners because we know it works. Rewards are already live on Avalanche Card, and the results speak for themselves. Over 30 days, cardholders with Rewards spent about 25% more per day than those not enrolled, compared with their previous spending history.
Capturing a lift like that used to mean the expensive, slow setup most programs couldn't justify. Now it's something a partner on Rain can add on top of what they already run. And for those still picking where to build their program, it's the difference between launching a card and launching one people keep coming back to. If you’re ready to explore what your business can unlock with Rain, let’s talk.
Estado de las stablecoins en América Latina
Última actualización: junio de 2026
Resumen ejecutivo
América Latina se ha consolidado como uno de los mercados de stablecoins más dinámicos del mundo. Entre 2022 y 2025, la región registró aproximadamente 1,5 billones de dólares en transacciones de criptomonedas, y las stablecoins respaldadas por el dólar estadounidense representaron la mayor parte de esos flujos, según datos de Chainalysis.. A inicios de 2025, se estimaba que 57,7 millones de personas en América Latina poseían monedas digitales, lo que representa cerca del 12 % de la población total de la región, según Coinchange.
La adopción de stablecoins en América Latina es estructural, no especulativa. Las stablecoins están resolviendo problemas concretos, como la preservación del poder adquisitivo en economías con alta inflación, reducir el coste y la latencia de los pagos transfronterizos y dar a personas y empresas acceso práctico al dólar estadounidense. Los avances regulatorios en gran parte de América Latina y un mayor acceso a plataformas de infraestructura impulsadas por stablecoins también han contribuido al aumento de su uso en la región.
Este informe examina cómo se utilizan las stablecoins en la práctica en toda América Latina. Aborda los factores estructurales detrás de la adopción, cómo difieren los casos de uso y los niveles de adopción según el país, quiénes son los principales actores de infraestructura y hacia dónde se dirige el panorama regulatorio.
¿Por qué stablecoins? Los factores estructurales de la adopción
La adopción de stablecoins en América Latina no es producto del entusiasmo por las criptomonedas. Es una respuesta a brechas persistentes que la infraestructura financiera tradicional no ha sabido resolver. Tres fuerzas impulsan la mayor parte de su uso en la región.
Fuerza 1: Inestabilidad monetaria y acceso al dólar
Varias de las principales economías latinoamericanas han atravesado periodos de inflación de dos o tres dígitos, controles de capital o escasez aguda de divisas. El peso argentino ha perdido más del 99 % de su valor frente al dólar estadounidense en la última década. Las reservas oficiales de divisas de Bolivia se desplomaron desde un máximo de 15.100 millones de dólares en 2014 hasta cerca de 1.700 millones en 2023. La escasez llevó a los bancos a restringir drásticamente el gasto con tarjetas en dólares y a cobrar comisiones elevadas en las transacciones internacionales, empujando a personas y empresas hacia los mercados informales y los tipos de cambio paralelos. En este entorno, las stablecoins denominadas en dólares como USDC y USDT funcionan como un instrumento práctico de ahorro y una vía para acceder al dólar estadounidense.
La misma lógica se aplica a nivel empresarial. El comercio internacional requiere una unidad de cuenta común, y el dólar estadounidense sigue siendo esa unidad en toda la región. Para las empresas que importan bienes, pagan a contratistas en el extranjero o facturan a clientes internacionales, mantener capital de trabajo en stablecoins respaldadas por el dólar elimina el riesgo de oportunidad en la conversión de divisas y simplifica la conciliación transfronteriza.
Fuerza 2: Comisiones altas y fricción en los pagos transfronterizos
Los flujos transfronterizos entre Estados Unidos y América Latina se encuentran entre los corredores de pago más significativos en lo económico —y, históricamente, más costosos— del mundo. En 2024, casi 170.000 millones de dólares en remesas fluyeron hacia América Latina y el Caribe, cerca del 80 % de ellas enviadas desde Estados Unidos.
El Banco Mundial estima que el costo promedio de enviar remesas a América Latina se mantiene entre el 5 % y el 7 %, según el corredor y el tamaño de la transferencia, con un promedio mundial situado en el 6,5 % en 2025. Además de las comisiones explícitas, quienes envían y reciben absorben costos a través de los diferenciales del tipo de cambio, los retrasos en la liquidación (por lo general de uno a tres días hábiles) y los cargos de los bancos intermediarios. Las transferencias basadas en stablecoins pueden reducir estos costos de manera sustancial.
Con las stablecoins, las comisiones de remesas pueden reducirse hasta en un 92 %. El monto exacto de la reducción depende del proveedor; algunos exchanges ofrecen un 0 % para el onramping y offramping de stablecoins, mientras que otros cobran hasta un 4,5 %. Una encuesta de 2026 a 4.600 usuarios en 15 países encontró que las transferencias con stablecoins cuestan en promedio un 40 % menos que los canales de remesas tradicionales.
Las stablecoins también están reduciendo los costos de los pagos transfronterizos entre empresas (B2B), como la nómina de contratistas y las transferencias de tesorería corporativa. El volumen de pagos B2B con stablecoins creció más de un 730 % interanual en 2025, con un total de pagos en stablecoins que alcanzó unos 390.000 millones de dólares, más del doble de los niveles de 2024. Las transacciones B2B representan ahora alrededor del 60 % de ese volumen. Bitso Business informa que el 45 % de su volumen institucional total en stablecoins corresponde a transacciones B2B y de tesorería corporativa.
Fuerza 3: Acceso bancario limitado
La infraestructura bancaria tradicional está fragmentada en toda América Latina. El Banco Mundial estima que, en 2021, 122 millones de adultos en la región no tenían acceso a una cuenta bancaria.
El acceso bancario ha mejorado en muchos países de la región con el auge de las fintech y los servicios de banca digital, pero la diferencia entre países sigue siendo enorme:
- México: Según el Global Findex 2025 del Banco Mundial, el 53 % de los adultos en México tenía una cuenta financiera en un banco, un servicio de dinero móvil u otra institución, lo que significa que cerca del 47 % no tenía ninguna cuenta financiera formal.
- Colombia: El acceso bancario en Colombia se ha expandido con rapidez en la última década. La titularidad de cuentas entre adultos pasó del 30 % en 2011 al 46 % en 2017 y al 57 % en 2024, según el Global Findex del Banco Mundial. Aun así, cerca del 43 % de los adultos seguía sin tener una cuenta financiera formal en 2024, lo que deja a una gran parte de la población dependiente del efectivo y fuera del sistema bancario formal.
- Brasil: Brasil se encuentra entre los mercados más bancarizados de la región, y el acceso ha aumentado marcadamente en la última década. Según el Global Findex del Banco Mundial, la proporción de adultos brasileños con una cuenta financiera subió del 70 % en 2017 al 84 % en 2021 y al 86 % en 2024. Pix, el sistema de pagos instantáneos del banco central lanzado en noviembre de 2020, ha sido un motor clave de ese cambio; para finales de 2025, cerca del 93 % de la población adulta lo usaba.
El panorama específico de la infraestructura bancaria de cada país determina cómo entran las stablecoins al mercado. En economías con mayores poblaciones no bancarizadas, las stablecoins pueden actuar como una alternativa de mercado paralelo. En mercados más bancarizados como Brasil, donde Pix ha alcanzado una adopción casi universal entre adultos, las plataformas fintech conectan cada vez más las stablecoins con los rieles de pago existentes —permitiendo a los usuarios mantener saldos denominados en dólares y retirarlos a reales mediante Pix— en lugar de depender de las stablecoins como un sistema financiero paralelo.
La estructura de costos: rieles tradicionales vs. stablecoins
Más allá de las comisiones explícitas, el mayor costo oculto en los pagos transfronterizos tradicionales es la prefinanciación (prefunding). Las empresas de remesas y de pagos B2B deben mantener cuentas pre financiadas — reservas de efectivo en bancos extranjeros — en cada país donde operan. Con un desfase de liquidación de dos a cinco días, una empresa que procesa 1 millón de dólares al día necesita tener entre 2 a 5 millones de dólares inmovilizados en cuentas de bancos corresponsales en todo momento, y eso se multiplica por cada corredor. Los rieles de stablecoins, en cambio, ofrecen financiación en tiempo real: la liquidación toma minutos en lugar de días, por lo que los requisitos de prefinanciación disminuyen significativamente. En 2025, Visa anunció un piloto de prefinanciación con stablecoins a través de Visa Direct, su plataforma global de pagos, señalando que la prefinanciación con stablecoins libera a las empresas de tener que estacionar grandes saldos en moneda fiduciaria por adelantado y permite a las instituciones mover dinero en minutos en lugar de días.
Adopción de stablecoins por país
La adopción de stablecoins en América Latina no es monolítica. Si bien su uso está muy extendido, los factores subyacentes difieren de manera notable según el país. Los siguientes perfiles destacan dónde se concentra la adopción y qué la impulsa.
Brasil
Brasil tiene el mercado de stablecoins más grande y estructuralmente más avanzado de la región. Las stablecoins representan aproximadamente el 90 % del volumen total de transacciones cripto del país. A diferencia de los mercados impulsados hacia las stablecoins principalmente por la alta inflación, la adopción de Brasil es el resultado de un cambio estructural más consolidado en su economía.
Una parte significativa del volumen de stablecoins en Brasil proviene de la actividad comercial. Brasil tiene una economía de comercio transfronterizo sofisticada, con una actividad de importación y exportación considerable y una amplia base de contratistas remotos. Las transferencias bancarias tradicionales conllevan diferenciales de cambio y demoras en la liquidación que las stablecoins reducen de manera notable, lo que las convierte en una opción atractiva para empresas y proveedores de nómina.
Cuando reciben pagos, las empresas suelen preferir mantener saldos en stablecoins respaldadas por el dólar en lugar de convertirlos de inmediato a reales. Esto reduce la exposición a la volatilidad cambiaria. La disponibilidad de Pix, que registró un aumento del 53 % en el volumen de pagos interanual en 2024, también ha creado una base para la integración de stablecoins de la que carecen otros mercados.
En el frente regulatorio, Brasil ha implementado uno de los marcos más completos de la región para los proveedores de servicios de activos virtuales (VASP, por sus siglas en inglés). Los VASP deben cumplir los mismos estándares regulatorios y de cumplimiento que otras instituciones financieras del país.
Los VASP también están sujetos a límites en las transacciones transfronterizas y a obligaciones detalladas de reporte sobre las operaciones cambiarias. El banco central reclasificó las transferencias transfronterizas de stablecoins como operaciones cambiarias en noviembre de 2025, lo que sometió a los proveedores de stablecoins a las mismas obligaciones de reporte y monitoreo de transacciones que los operadores de cambio tradicionales.
Funcionarios de Brasil han planteado extender el impuesto IOF (Imposto sobre Operações Financeiras) a los flujos de stablecoins, lo que cerraría la brecha regulatoria que actualmente hace que los rieles de stablecoins sean más baratos que los canales cambiarios tradicionales para transacciones transfronterizas. Grupos del sector que representan a más de 850 empresas se han opuesto, argumentando que sería ilegal y perjudicaría la innovación, y en marzo de 2026 el ministro de Hacienda aplazó la consulta sobre el impuesto en medio de tensiones con el Congreso en año electoral. La cuestión sigue sin resolverse y es uno de los asuntos regulatorios más trascendentales de la región para 2026.
En abril de 2026, el banco central fue más allá con la Resolución BCB n.º 561, que prohíbe a los proveedores regulados de cambio electrónico —instituciones de pago, emisores de dinero electrónico y adquirentes— usar stablecoins u otras criptomonedas para liquidar el tramo offshore de los pagos transfronterizos. A partir de octubre de 2026, la liquidación con contrapartes en el extranjero deberá realizarse mediante operaciones cambiarias tradicionales o cuentas en reales de no residentes. La actividad cripto de las personas no se ve afectada, y los proveedores de servicios de activos virtuales con licencia aún pueden usar stablecoins para pagos transfronterizos bajo el marco independiente de la Resolución 521. Los analistas esperan que la norma eleve el costo de los pagos transfronterizos y las remesas al reintroducir los diferenciales bancarios, las comisiones de corresponsalía y la liquidación de varios días, donde los rieles de stablecoins habían ofrecido transferencias casi instantáneas y de menor costo.
Bolivia
La adopción de stablecoins en Bolivia está moldeada por una aguda crisis cambiaria. Las reservas oficiales de divisas del país se desplomaron desde un máximo de 15.100 millones de dólares en 2014 hasta cerca de 1.700 millones en 2023, y las reservas líquidas en dólares del país cayeron a 73 millones de dólares a finales de 2025. El acceso limitado a los dólares, sumado a los límites al gasto para tarjetas en dólares, ha empujado a las personas hacia los mercados informales con tipos de cambio paralelos. En este entorno, las stablecoins se han convertido en un sustituto funcional para acceder adólares.
A nivel empresarial, las compañías que dependen de bienes importados realizan cada vez más los pagos a sus proveedores extranjeros en USDT o USDC, adquiridos a través de plataformas P2P u OTC. A nivel de los consumidores, startups como Meru —una billetera cripto local construida sobre Stellar— habilitan pagos cotidianos con stablecoins, permitiendo a los usuarios comprar en comercios locales mediante códigos QR y en comercios globales mediante tarjetas emitidas por Rain, lo que permite a los consumidores realizar más compras globales de las que de otro modo podrían hacer.
Bolivia es uno de los mercados latinoamericanos en los que Rain tuvo mayor crecimiento, con un gasto con tarjeta que creció más de 6 veces en 2025. Casi toda esa actividad es transfronteriza. Tanto empresas como consumidores usan tarjetas financiadas con stablecoins para comprar bienes y servicios internacionales que no pueden pagar fácilmente en moneda local.
Argentina
Por el lado de Argentina, la adopción de stablecoins está impulsada principalmente por la inflación. Años de inflación severa —que alcanzó un pico cercano al 300 % en 2024 antes de moderarse a alrededor del 30 % en 2025—, combinada con controles de capital y restricciones cambiarias, han convertido a las stablecoins respaldadas por el dólar en un instrumento de ahorro por defecto para muchos hogares y pequeñas empresas.
La escala de esa demanda es amplia. Argentina fue el segundo mercado cripto más grande de América Latina entre julio de 2022 y junio de 2025 por volumen de transacciones, con 93.900 millones de dólares, solo por detrás de Brasil, y las stablecoins constituyen más de la mitad de todas las compras en exchanges cripto del país. La inflación, la volatilidad cambiaria y los controles de capital empujan a hogares y empresas hacia la estabilidad vinculada al dólar para el ahorro, las remesas y el comercio.
En el frente regulatorio, Argentina ha pasado de un mercado en gran medida informal hacia un marco más definido. Bajo la presidencia de Milei, las actitudes hacia las criptomonedas se volvieron notablemente más permisivas, y en 2025 el regulador de valores (CNV) introdujo un régimen de registro obligatorio para los proveedores de servicios de activos virtuales. El banco central también ha avanzado hacia permitir que los bancos ofrezcan servicios cripto, lo que señala un cambio gradual desde los canales peer-to-peer y de exchanges hacia una mayor participación institucional.
Colombia
En Colombia, el uso de stablecoins se concentra principalmente en el movimiento transfronterizo de dinero y los pagos de remesas. El mercado de remesas de Colombia suma aproximadamente 10.000 millones de dólares al año y alcanza al 40% de la población, impulsado en los últimos años por una moneda local débil. En ese contexto, las stablecoins ofrecen una alternativa a los proveedores de remesas tradicionales al brindar una liquidación más rápida y, a menudo, a menor costo.
Recientemente, MoneyGram estrenó su aplicación impulsada por stablecoins con Colombia como primer mercado, ratificando su condición de corredor de remesas entrantes clave y la fuerte demanda de activos vinculados al dólar en medio de la depreciación del peso.
Más allá de las remesas de consumidores, el uso de stablecoins en Colombia ha crecido entre empresas y contratistas, en particular para la facturación transfronteriza, los pagos a proveedores y la gestión de tesorería. La legislación colombiana exige que los pagos entre residentes nacionales se liquiden en pesos, lo que limita el uso de stablecoins en transacciones puramente nacionales. Sin embargo, estas restricciones no aplican a los pagos transfronterizos.
Cabe destacar que el 99% de las compras realizadas con pesos colombianos en exchanges de criptomonedas centralizados se canalizan directamente hacia stablecoins, lo que sugiere que, para la mayoría de los usuarios, los activos denominados en dólares son la razón principal para entrar al mercado de activos digitales. Colombia ocupa el quinto lugar en América Latina con respecto a volumen total de transacciones cripto con 44.200 millones de dólares, por detrás de Brasil, Argentina, México y Venezuela. El número de titulares de tarjetas emitidas por Rain en Colombia se ha multiplicado por 64 desde inicios de 2025.
México
México recibió un récord de 64.700 millones de dólares en remesas en 2024, enviadas en su gran mayoría desde Estados Unidos. Es el corredor de remesas individual más grande del mundo, superando los 55.000 millones de dólares en 2022. Lo que hace que la adopción de stablecoins en este mercado sea particularmente notable es que este corredor ya es uno de los más competitivos y líquidos de los pagos globales. Grandes proveedores como Western Union, MoneyGram y Wise han invertido significativamente en los pagos de Estados Unidos a México, y la infraestructura de pagos instantáneos SPEI de México permite la liquidación en pesos el mismo día.
A pesar de este acceso, las stablecoins están ganando una participación de mercado significativa. Las stablecoins se utilizan cada vez más para pagos de remesas, y tan solo Bitso Business procesó aproximadamente el 10 % del total de pagos de Estados Unidos a México. Las stablecoins representaron el 36 % de las compras de criptomonedas en México en la primera mitad de 2025, lideradas por USDC, lo que aún está por debajo del promedio latinoamericano del 46%.
Uruguay
Con condiciones macroeconómicas relativamente estables y una población altamente bancarizada —aproximadamente el 74 % de los adultos posee una cuenta financiera—, la adopción de stablecoins en Uruguay está menos impulsada por la crisis y más por la infraestructura.
El país promulgó en 2024 la Ley N.º 20.345 que reconoce formalmente los activos virtuales y asigna la supervisión al Banco Central del Uruguay, creando una de las vías de cumplimiento más claras de la región para exchanges y plataformas de pago. La claridad regulatoria ha contribuido a impulsar la innovación fintech en Uruguay.
En toda la región, la claridad regulatoria se correlaciona fuertemente con la participación institucional. Los mercados con marcos de supervisión definidos, como Brasil y Uruguay, registran una mayor integración por parte de bancos, proveedores de remesas y procesadores de pagos.
Actores clave en la región
Exchanges y plataformas institucionales
Bitso
Bitso es una de las mayores plataformas criptomonedas de América Latina, con más de 10 millones de usuarios minoristas y más de 2.000 clientes institucionales. Bitso procesó cerca del 10 % del mercado total de remesas entre Estados Unidos y México.
Su división institucional, Bitso Business, superó los 80.000 millones de dólares en volumen total de pagos anualizado en 2025, convirtiéndose en la mayor plataforma de pagos con stablecoins de la región. Más allá de las remesas, Bitso Business ofrece un conjunto de servicios empresariales que incluye cuentas multidivisa, pagos, cambio de divisas (FX) y FX como servicio, trading, orquestación de stablecoins y gestión de tesorería en México, Argentina, Brasil, Colombia, Chile, Perú, Estados Unidos y Europa. El 45 % de su volumen institucional corresponde a transacciones B2B y de tesorería corporativa, y la adopción de stablecoins entre sus clientes institucionales se duplicó entre el segundo semestre de 2024 y el primer semestre de 2025. Tan solo los flujos de pagos locales en México superaron los 15.000 millones de dólares en 2025, consolidando a Bitso Business como un proveedor de infraestructura clave para las empresas globales que operan en el país.
Bitso también se ha expandido hacia la emisión de stablecoins. Lanzó MXNB, una stablecoin respaldada por el peso mexicano emitida a través de su subsidiaria Juno, y colanzó BRL1, una stablecoin vinculada al real brasileño, junto con Mercado Bitcoin, Foxbit y Cainvest.
Ripio
Ripio es uno de los mayores exchanges de criptomonedas más grandes de América Latina, con operaciones en Argentina, Brasil, México y otros mercados. Además de sus servicios de exchange, Ripio ha desarrollado un conjunto de stablecoins vinculados a monedas locales, incluyendo wARS (peso argentino), wBRL (real brasileño) y wMXN (peso mexicano), diseñadas para facilitar los pagos denominados en moneda local y la liquidaciones transfronterizas sin requerir conversión a dólares. El conjunto de stablecoins locales posiciona a Ripio no solo como un exchange, sino también como capa de infraestructura para el comercio regional.
Neobancos
Mercado Pago
Mercado Pago es la división de pagos de Mercado Libre, la mayor plataforma de comercio electrónico de América Latina. Mercado Pago lanzó MeliDolar (MUSD), una stablecoin respaldada por el dólar desarrollada en asociación con Ripio, actualmente disponible en Brasil, México y Chile. En septiembre de 2025, más de 65 millones de dólares estaban en circulación. Mercado Libre descontinuó recientemente su token cripto original, Mercado Coin, que se utilizaba para los saldos de recompensas en la plataforma. En adelante, la plataforma ofrecerá recompensas a través de MUSD.
Nubank
Nubank es el neobanco más grande de América Latina, con más de 130 millones de clientes en Brasil, México y Colombia. Su oferta de productos incluye cuentas digitales, tarjetas, préstamos y servicios de inversión. Nubank incorporó soporte para stablecoins en diciembre de 2023 y comenzó a ofrecer rendimiento sobre USDC en enero de 2025, convirtiéndose en una de las primeras instituciones financieras de la región en hacerlo. USDC es el segundo activo más popular entre los clientes que realizan su primera compra de cripto.
Billeteras y plataformas de pago
Belo
Belo es una importante plataforma fintech para individuos que opera principalmente en Argentina, y que está expandiendo por toda América Latina. Belo permite a sus usuarios mantener stablecoins que generan intereses a través del protocolo DeFi de Aave, así como gastar, transferir o recibir pagos tanto en moneda local como en stablecoins. Su base de usuarios representa más del 8 % de los usuarios de cripto activos de la región. Belo se destaca por cerrar la brecha entre el ahorro, el rendimiento y el gasto cotidiano dentro de una sola interfaz, un modelo que otras plataformas están empezando a replicar. Los usuarios de Belo acceden a comercios globales mediante tarjetas emitidas por Rain.
Meru
Construida sobre Stellar, Meru es uno de los principales ejemplos de adopción de stablecoins en el mundo real en América Latina. La plataforma de Meru permite a individuos y a empresas en Bolivia acceder a dólares digitales, realizar pagos locales mediante códigos QR y transaccionar a nivel global a través de tarjetas emitidas por Rain.
Al proporcionar acceso a tasas de cambio competitivas con el mercado y pagos fluidos con USDC, Meru ayuda a los usuarios a preservar valor, reducir costos de transacción y participar de manera más efectiva tanto en el comercio local como en el internacional. La plataforma demuestra cómo las stablecoins pueden resolver desafíos económicos tangibles e impulsar la inclusión financiera en mercados con acceso limitado al dólar.
Takenos
Takenos es una plataforma financiera de individuos enfocada en el movimiento transfronterizo de dinero y los pagos globales en América Latina. Permite a freelancers y contratistas recibir pagos transfronterizos, mantener saldos en stablecoins y otras monedas, y gastar o transferir fondos en 20 países. Construida sobre Solana, Takenos ha procesado más de 560 millones de dólares en volumen y reportó un crecimiento de alrededor del 20 % mes a mes a lo largo del 2025, con una ronda semilla de 10 millones de dólares coliderada por Variant y Lattice. Takenos habilita el gasto transfronterizo mediante tarjetas emitidas por Rain.
Félix Pago
Félix es una empresa de remesas y servicios financieros nativa dentro de WhatsApp, creada para los inmigrantes latinos en Estados Unidos. La compañía permite a los usuarios enviar dinero a América Latina con la misma facilidad con la que se envía un mensaje, utilizando stablecoins como USDC como parte de su infraestructura de liquidación operacional con un interfaz simple. En lugar de exponer a los usuarios directamente a las criptomonedas, Félix aprovecha los rieles de stablecoins para reducir las ineficiencias operativas y de cambio de moneda, mejorar la velocidad de liquidación y conectar los flujos de dólares estadounidenses con las redes de pago locales en toda América Latina. Félix ha procesado más de 6.000 millones de dólares en remesas y actualmente atiende corredores claves entre Estados Unidos y América Latina, incluidos México, Guatemala, Honduras, El Salvador, Nicaragua, Colombia, la República Dominicana, Ecuador y Perú.
Stablecoins en dólares versus stablecoins en moneda local
Dado que acceder al dólar estadounidense sigue siendo una de las principales razones por las que empresas e individuos usan stablecoins, los mayores tokens utilizados en América Latina siguen estando respaldados por el dólar. USDT y USDC en conjunto representan más del 90 % del volumen de transferencias de stablecoins en los exchanges a mediados de 2025. Las stablecoins en dólares pasaron de alrededor del 60 % en 2022 a más del 90 % en 2025. Para la mayoría de los casos de uso transfronterizos y de tesorería, los tokens en dólares son la opción natural por defecto, al ofrecer liquidez profunda, una aceptación casi universal y una unidad de cuenta común para el comercio internacional.
Pero el acceso al dólar no es el único componente atractivo. Las stablecoins en moneda local, como BRL1, anclada al real brasileño, permiten a las empresas fijar precios, facturar y liquidar a nivel nacional sin convertir hacia y desde el dólar, y ofrecen a los consumidores una versión más funcional del dinero que ya poseen. La disyuntiva se reduce a la liquidez y la aceptación: los tokens en dólares ofrecen utilidad transfronteriza, pero pueden requerir conversión para la fijación de precios domésticos, mientras que los tokens locales reducen la fricción cambiaria nacional, pero dependen de la claridad regulatoria y de la integración bancaria para poder escalar. Los volúmenes actuales sugieren que las stablecoins en dólares seguirán dominando al mercado para las funciones transfronterizas y de tesorería, mientras que los tokens locales crecerán dentro de ecosistemas nacionales regulados.
Conclusión
En los últimos años, la adopción de stablecoins en América Latina ha pasado de unos pocos casos de uso limitados a convertirse en uno de los ecosistemas más diversos y activos del mundo.
Los factores de adopción en la región varían según el país. La inestabilidad monetaria, los costosos rieles transfronterizos y el acceso bancario desigual son características estructurales de la economía de la región. Mientras esas condiciones persisten, es probable que la demanda de ahorro, pagos y gestión de tesorería denominados en stablecoins siga creciendo junto con la infraestructura que se está construyendo para sostenerla.
De cara al futuro, los cambios regulatorios en toda la región van a influir en la forma en que tanto consumidores como empresas interactúan con las stablecoins. Los casos de uso que han tomado forma en América Latina, y la infraestructura que se está construyendo para sostenerlos, representan algunos de los ejemplos del mundo real más claros de cómo las stablecoins están impactando de manera significativa la forma en que consumidores y empresas operan financieramente.
Introducing the Agent Control Layer
Rain's Agent Control Layer gives businesses and developers precise, programmatic control over how AI agents spend using cards and move money on behalf of users. Partners define the conditions under which an agent can transact, and Rain enforces them before any money moves.
Agents have been transacting on Rain's infrastructure in production for months. They book travel, subscribe to software, run procurement workflows, and move money globally. To scale that activity, businesses need to bound what an agent can do, keep its activity auditable, and adjust the limits as workflows grow. The Agent Control Layer provides that framework.
The controls are enforced at card issuance and transfer initiation rather than applied after the fact. By the time an agent attempts to transact, the governing rules are already in place, and a transaction that falls outside them does not proceed.
Card controls
Rain's scoped virtual card infrastructure already supports agent purchases. The Agent Control Layer adds two levels of control on top of it.
At the agent level, users define what their agent can do before it acts: transaction amounts, merchant and category allowlists, spend intervals, and card expiry. An agent issued a card for a single booking can be limited to approved airlines or hotels, capped at a set amount, and restricted to a defined window. Outside those parameters, the card does not transact.
At the program level, partners manage risk across their entire user base, with caps on the number of active cards, aggregate spend limits, and the visibility to identify unusual activity early.
Sponge, a Y Combinator-backed company building for autonomous agents, is one of the partners issuing agent-usable cards on Rain today. Its cards are funded by a user's stablecoin balance and let agents transact anywhere Visa is accepted online, across more than 175 million merchant locations.
Money movement controls
The same controls extend across Rain's money movement suite: virtual accounts, onramps, offramps, and fiat and stablecoin payments to individuals and businesses. Partners define approved counterparties, amounts, frequency, and timing before an agent is permitted to act.
A business that enables agents to manage vendor payments can restrict those agents to approved vendors, on a defined schedule, for a defined amount. Changes to those terms require explicit action by a human administrator.
Available in beta
The Agent Control Layer is available in beta. Businesses tracking the autonomous payments category now have production-ready infrastructure and a governance framework built for machine actors, and can begin running real workflows rather than waiting for the category to mature.
It is the latest piece of Rain's ongoing work in agentic payments, which spans compliance frameworks built for autonomous actors, programmable settlement across cards, bank rails, and blockchains, and interoperability with emerging agentic commerce protocols, including early work on the open standards we believe the industry will need to build together.
Reach out to the team to book a demo.
Machine-initiated payments will unlock new opportunities for payment credentials
It’s rare for a change in consumer payments to justify rebuilding the foundation, but few innovations have been quite as disruptive as agentic commerce.
For nearly sixty years, the card payment credential, personal account number (PAN), has been a static, reusable identifier riding on rails designed for human-initiated transactions. The 16-digit account number was introduced in the 1960s as a way to extend a line of credit to a specific person at a specific bank. In the world Visa designed this in, with paper slips, carbon copies, in-person purchases at the point of sale, the design made sense. More than 60 years later, though, nearly every payment protocol still assumes the same factors in each transaction: a credential tying an account to a cardholder, a merchant, and a moment of human consent at the point of sale.
Commerce itself has changed dramatically since the 1960s. The rise of e-commerce stripped away the physical signals — a card in hand, a signature, a clerk — that the original model relied on, and the industry had to invent new ones to keep the system running. CVV2 and address verification were grafted on to stand in for physical presence. PCI-DSS set rules for how merchants could store the PAN.
EMV 3-D Secure, introduced in 2001 and refreshed as 3DS 2 in 2016, layered cryptographic authentication on top of that flow. Network tokenization, which Visa launched in 2014 and was standardized across the industry in the following years, replaced the PAN at point of use so the real account number never traveled with the transaction. Each of these was a real upgrade, and together they made online commerce workable at scale. But each was a layer wrapped around the same credential. A human still types or pastes the same 16-digit number into a checkout field, and the system still treats that act as proof of intent. E-commerce demanded changes around the credential, not to it. That work is still ahead.
When agents are the buyer, the credential has to carry more than account identity. At Rain today, this happens at issuance. Agents transact using scoped virtual cards that are customized to work at approved merchants under specific conditions. Consumers and businesses directing agents to buy on their behalf go through the same KYC and KYB procedures their cards have always required. This model operates within the rails merchants already accept, which matters because agent purchases need to land in the same checkout flows human purchases do, certainly in the near term, and likely in the future, too.
Cards, however, were not designed for what comes after this. The next wave of agentic commerce is not agents using cards to check out at the same merchants as humans, but machine-to-machine payments, where the buyer is software, the seller is software, and consent must travel inside the credential itself rather than sit at the moment of issuance. A credential whose only job is to identify an account cannot express what an agent is allowed to do; only that an account exists.
The design space for what comes next is wide open, but we see a few things as non-negotiable. An agentic payment credential needs to clearly identify the funding source behind the transaction, so issuers, merchants, and networks know who is ultimately on the hook. It needs to carry the human-approved constraints under which the agent is authorized to spend. This means which merchant, what amount, for how long, on whose behalf, under what conditions, and by what means it can be revoked. And it needs to be auditable, both for the human who delegated spend authority and for the broader set of parties — issuers, networks, regulators — responsible for consumer protection. These properties are what turns an account identifier into a record of consent.
The implications of this extend beyond the technical layer. Moving consent into the credential changes what an authorization request actually verifies, what a merchant can directly confirm about who authorized the transaction, and how disputes are resolved when the buyer is not human. This model will support microtransactions and programmatic commerce between services that current rails cannot economically serve, and allow for consumer protections that operate through constraint rather than detection. The scope of what an agent can do will be defined in advance, not inferred from behavior after the fact.
Most of the changes to consumer payments over the past two decades have been refinements within the same model. The shift that agentic commerce requires is structural; the credential has to account for who, or what, is actually transacting.
Rain integrates Monad, bringing card programs to the financial layer of the internet
Rain now supports Monad, the high-performance Layer 1 bringing parallel execution to the EVM.
A crucial component of the internet financial layer is efficient and scalable payments capabilities. This integration gives fintechs and crypto-native builders a new option for issuing cards and running high-volume payment programs.
For Rain partners looking to launch a stablecoin card, payroll product, or cross-border remittance flow, the underlying chain infrastructure needs to handle real transaction volume without fees spiking during busy periods. Monad processes transactions in parallel rather than one-by-one, which keeps costs flat and confirmations fast even when usage climbs. Monad’s architecture is designed for full functionality and money movement as volume scales.
Stablecoin-backed cards put real demands on blockchain infrastructure. Card networks operate on tight timing windows, and the onchain leg of a transaction needs to keep pace. Monad's sub-second deterministic finality is well-matched to those requirements, opening up card-native products that can compose onchain operations at the speed of a card tap.
For Rain partners building on Monad, that means a few key things:
- Predictable fees at scale, which matters when you're modeling unit economics on millions of small-ticket transactions.
- Full EVM compatibility, so any team already building on Ethereum can turn on Monad support without rewriting their stack.
- As card functionality continues to integrate blockchain technology, card authorizations will settle in well under a second, so the onchain leg never holds up the swipe.
For Rain, adding Monad is part of a broader effort to extend card-issuing infrastructure to the chains where partners are building. Each new chain integration is custom work. Our protocol engineers design and implement tailored smart contracts and outside auditors review everything before it goes live. Ongoing audits after a protocol goes live on Rain help keep the system secure as programs grow.
"Adding Monad gives builders a high-performance option without asking them to compromise on what they can launch.” Charles Yoo-Naut, Rain Co-founder and CTO, said. “Monad's architecture lines up with what consumer payments require at scale and allows us to explore new experiences only possible on the most performance chains.
Companies already building with Rain and Monad
For Monad, Rain bolsters an expanding payments ecosystem. A growing set of fintechs and payment platforms are looking to leverage Rain and Monad to bring stablecoin-powered card programs to market. These include:
- Rhythmic – building consumer payment products with embedded stablecoin rails
- Avici – developing programmable money experiences and stablecoin-native financial tools
These teams are actively building with Monad’s high-throughput, low-latency infrastructure, combined with Rain’s card issuing stack, to unlock new categories of real-world payment applications.
Adding Monad to the Rain platform reflects continued demand from partners looking to build on infrastructure that can support the workloads consumer payments produce.
“The Rain integration opens up more optionality for businesses and retail users alike to use Visa cards on Monad,” Raj Parekh, Head of Stablecoins and Payments at Monad Foundation, said. “Sub-second onchain transaction finality is critical in order for card issuers and neobanks to scale stablecoin card activity and this is something Monad uniquely unlocks.”